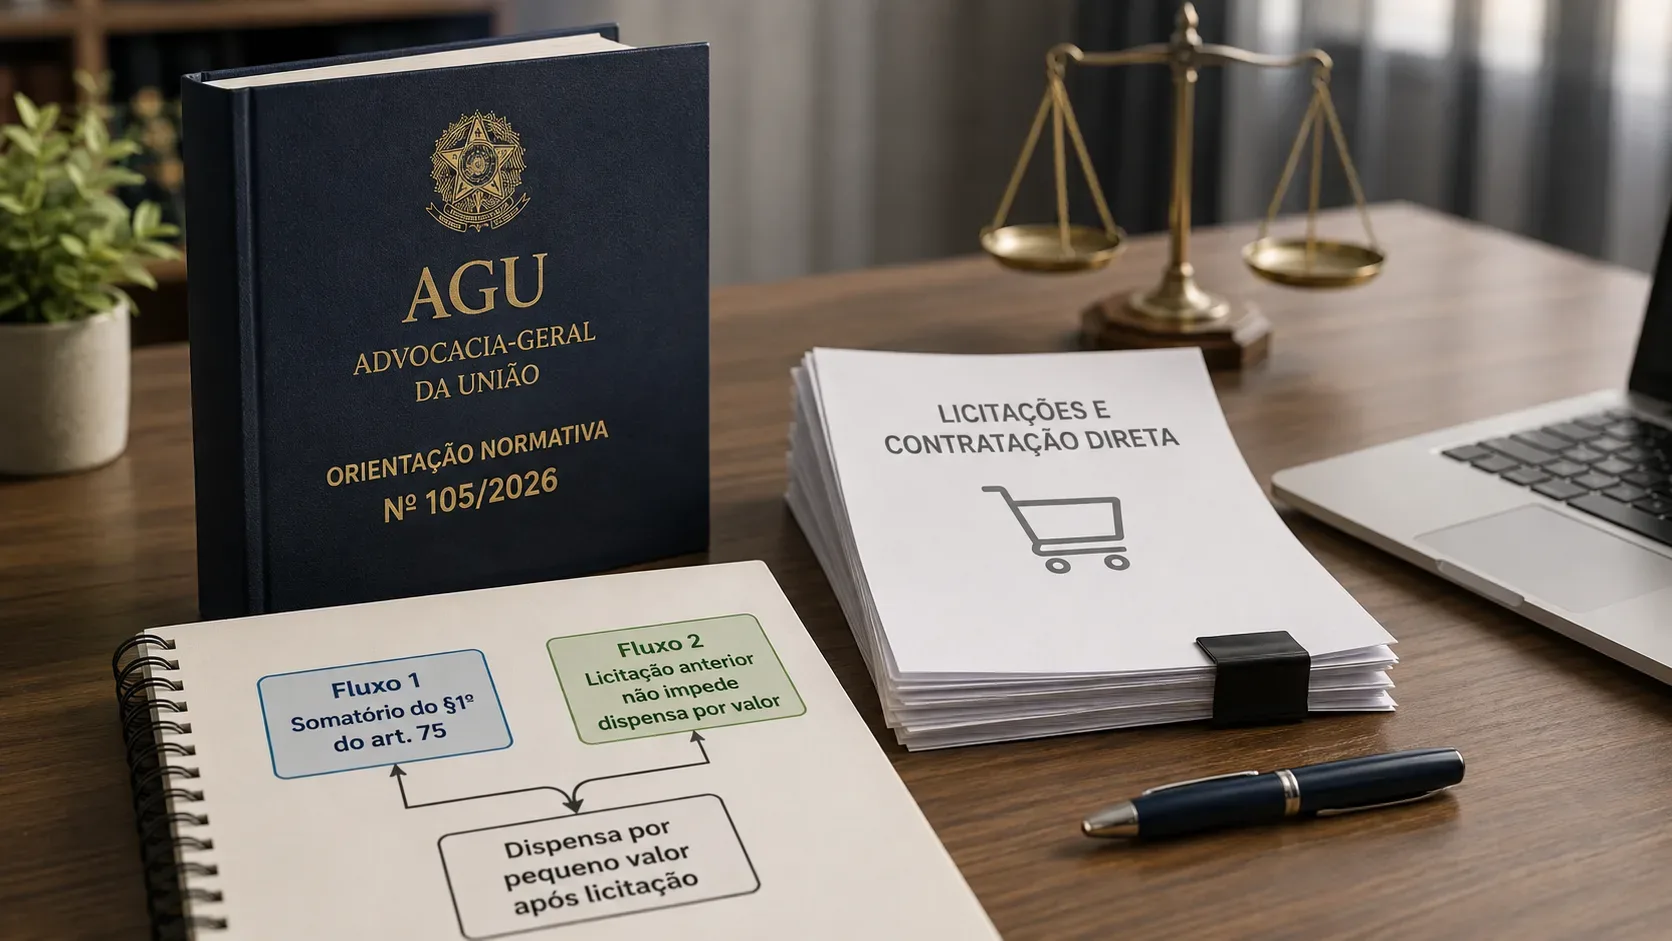
AGU Normative Guidance No. 105/2026 clarifies two practical questions about low-value direct contracting under items I and II of Article 75 of Brazil’s Law No. 14,133/2021. The first is what must be included in the calculation under paragraph 1 to determine whether the annual threshold has been respected. The second is whether a prior contract awarded through a competitive tender prevents the Administration from later using the low-value waiver for the same subject matter. AGU’s answer is restrictive for the calculation and conditional for the second situation: the aggregation covers only low-value waivers and acquisitions made through an imprest/petty-cash mechanism (suprimento de fundos); and a prior tender does not, by itself, prevent direct contracting, provided there is an unforeseen situation, an amendment to the prior contract is not possible, procurement planning is respected, and the statutory threshold remains available.
What AGU Normative Guidance 105/2026 clarified
Item I of Guidance 105/2026 states that the calculation under paragraph 1 of Article 75 applies exclusively to low-value waivers under items I and II and to acquisitions made through suprimento de fundos. The guidance also states that other forms of direct contracting are not included in this calculation, expressly including non-competitive contracting due to impossibility of competition (inexigibilidade), even when implemented through the auxiliary credentialing procedure.
Item II addresses a different situation: a tender has already been conducted for the subject matter, but an unforeseen need subsequently arises. In that case, AGU accepts that a new low-value direct contract may be considered for the same subject matter if the need cannot be addressed through an amendment and if procurement planning and the paragraph 1 threshold are respected.
The official text is available on AGU’s Normative Guidance page. The statutory basis remains Article 75 of Law No. 14,133/2021.
Flow 1: what is included in the paragraph 1 aggregation
Paragraph 1 requires control of spending during the fiscal year by the relevant management unit and of spending on objects of the same nature, defined by the law as contracts within the same line of business. Guidance 105/2026 defines which types of contracting feed this control when the Administration intends to rely on items I or II.
| Prior expense or contracting route | Included in the paragraph 1 calculation? | Practical reading |
|---|---|---|
| Low-value waiver under Article 75(I) | Yes | It must be included in the relevant accumulated amount for the fiscal year, management unit, and objects of the same nature. |
| Low-value waiver under Article 75(II) | Yes | It also counts toward the applicable threshold control. |
| Acquisition through suprimento de fundos | Yes | The Guidance expressly includes these acquisitions in the calculation. |
| Inexigibilidade (direct contracting where competition is not feasible) | No | The Guidance excludes other direct-contracting routes and expressly mentions inexigibilidade. |
| Inexigibilidade implemented through credentialing | No | Using credentialing as an auxiliary procedure does not change the exclusion identified by the Guidance. |
| Other direct-contracting grounds that are not Article 75(I) or (II) | No | They do not feed the specific paragraph 1 calculation under item I of the Guidance. |
| Contract awarded through a competitive tender | No | Because the calculation is limited to the categories identified by the Guidance, the tendered amount is not part of this specific aggregation. |
This does not mean that excluded contracts may be ignored for planning purposes. The Guidance defines the calculation of the low-value waiver threshold; it does not remove the duty to understand total demand, justify quantities, prevent improper splitting, or choose the most appropriate procurement strategy.
How to calculate it in practice
To apply paragraph 1 together with Guidance 105/2026, the responsible team should identify the management unit, fiscal year, and line of business associated with the object. It should then determine what has already been spent, within that scope, through low-value waivers under items I and II and through suprimento de fundos acquisitions of the same nature. That accumulated amount is then compared with the applicable threshold.
A prior contract awarded through an auction, competitive procedure, or another tender method may remain relevant to demand history, pricing, consumption, and planning, but it does not enter the specific aggregation defined by the Guidance.
Flow 2: when a prior tender does not prevent a low-value waiver
Guidance 105/2026 does not create a blanket authorization to contract directly after any tender. Item II makes the possibility dependent on a set of elements that should be documented in the administrative file.
- There must be an unforeseen situation. The new need cannot simply be the automatic continuation of a demand that was already known and predictable.
- An amendment must be unavailable. Before using a new waiver, the Administration should explain why the contract resulting from the prior tender cannot lawfully be amended to meet the need.
- Planning remains mandatory. Direct contracting cannot be used as a shortcut to remedy recurrent planning failures.
- The paragraph 1 threshold must remain available. The new expense must fit within the accumulated amount of the contracts that actually count under item I of the Guidance.
The key is to separate two questions. The first is: “how much has already been spent through contracts that consume the low-value waiver threshold?”. The second is: “is there a substantive justification for a new direct contract after the tender?”. The Guidance answers both, but a favorable threshold calculation does not replace the need to demonstrate the unforeseen situation and the impossibility of an amendment.
Do not confuse Guidance 105/2026 with Article 75(III)
Article 75(III) contains another waiver ground: it allows the Administration to maintain the conditions of a tender conducted less than one year earlier when no interested bidders or valid proposals appeared, or when the submitted prices were manifestly above market or official benchmarks. Guidance 105/2026 addresses a different legal logic.
Under item II of the Guidance, the prior tender does not have to be classified as deserted or failed for the issue to be considered. The focus is on a subsequent unforeseen need, the impossibility of an amendment, and the availability of a low-value waiver under items I or II. The requirements of Article 75(III) therefore should not be mixed with the conditions described by the Guidance.
Example of application
Suppose a management unit tendered a maintenance service and signed a contract. Months later, an additional need arises that could not reasonably have been anticipated in the original planning. The team determines and documents that the existing contract cannot be amended to absorb the new need. The value of the additional requirement is small.
In that scenario, the amount already contracted through the prior tender is not added to the specific paragraph 1 threshold under the reading of item I of the Guidance. The unit must, however, verify how much it has already spent in the same fiscal year and line of business through low-value waivers and suprimento de fundos acquisitions. If the new amount fits within the threshold, the case may proceed for analysis — provided the unforeseen situation, the impossibility of an amendment, value-for-money, and the other legal requirements are documented.
If the additional need was predictable, if the prior contract could lawfully be amended, or if the accumulated expenses that count under paragraph 1 have already reached the threshold, Guidance 105/2026 does not provide a basis to bypass those obstacles.
What are the 2026 thresholds?
For fiscal year 2026, Decree No. 12,807/2025 updated the amounts in Law No. 14,133/2021. The reference amount under Article 75(I) is BRL 130,984.20 for construction works and engineering services and for motor-vehicle maintenance services. The reference amount under Article 75(II) is BRL 65,492.11 for other services and purchases. The statute uses the wording “amounts below” these thresholds.
The amounts are periodically updated, so the administrative file should always confirm the figure in force for the fiscal year in which the contract is made. Decree No. 12,807/2025 took effect on January 1, 2026.
Checklist for the file after a prior tender
- Confirm that the new contract actually falls under Article 75(I) or (II).
- Identify the management unit, fiscal year, and line of business associated with the object.
- Add up the relevant low-value waivers and same-nature suprimento de fundos acquisitions.
- Do not include tenders or other direct-contracting routes excluded by the Guidance in that aggregation, while retaining those records in the planning history.
- Describe the event that made the new need unforeseen and record when it occurred.
- Explain why the contract resulting from the prior tender cannot be amended to address the need.
- Document the estimated expenditure, price justification, choice of contractor, qualification, and budget availability as required by Article 72 of Law No. 14,133/2021.
- Record value-for-money and consistency with the unit’s procurement planning.
- Submit the classification for competent legal review when applicable, especially when there is doubt about the nature of the object, the aggregation, or the impossibility of an amendment.
What Guidance 105/2026 does not authorize
The Guidance does not turn the low-value waiver into a routine mechanism for supplementing tendered contracts. It does not remove controls against improper contract splitting, permit the applicable threshold to be exceeded, waive the documentation required for direct contracting, or replace the amendment analysis when an amendment is legally possible.
Another important caution is not to use the exclusion of certain expenses from the aggregation as a reason to fragment a known requirement. The fact that a tender or an inexigibilidade contract does not consume the specific paragraph 1 threshold does not erase the planning duties imposed by Law No. 14,133/2021.
In summary
Guidance 105/2026 can be applied through two flows. First, the paragraph 1 calculation under Article 75 includes only low-value waivers under items I and II and suprimento de fundos acquisitions, considering the fiscal year, management unit, and objects of the same nature. Second, a prior tender for the same subject matter does not automatically prevent a new low-value waiver: there must be an unforeseen situation, no viable amendment, adequate planning, and remaining room under the applicable threshold.
For administrative decisions, the conclusion should be documented using the facts of the specific case and submitted to human legal review whenever required by the agency’s governance structure or when interpretive controversy remains.