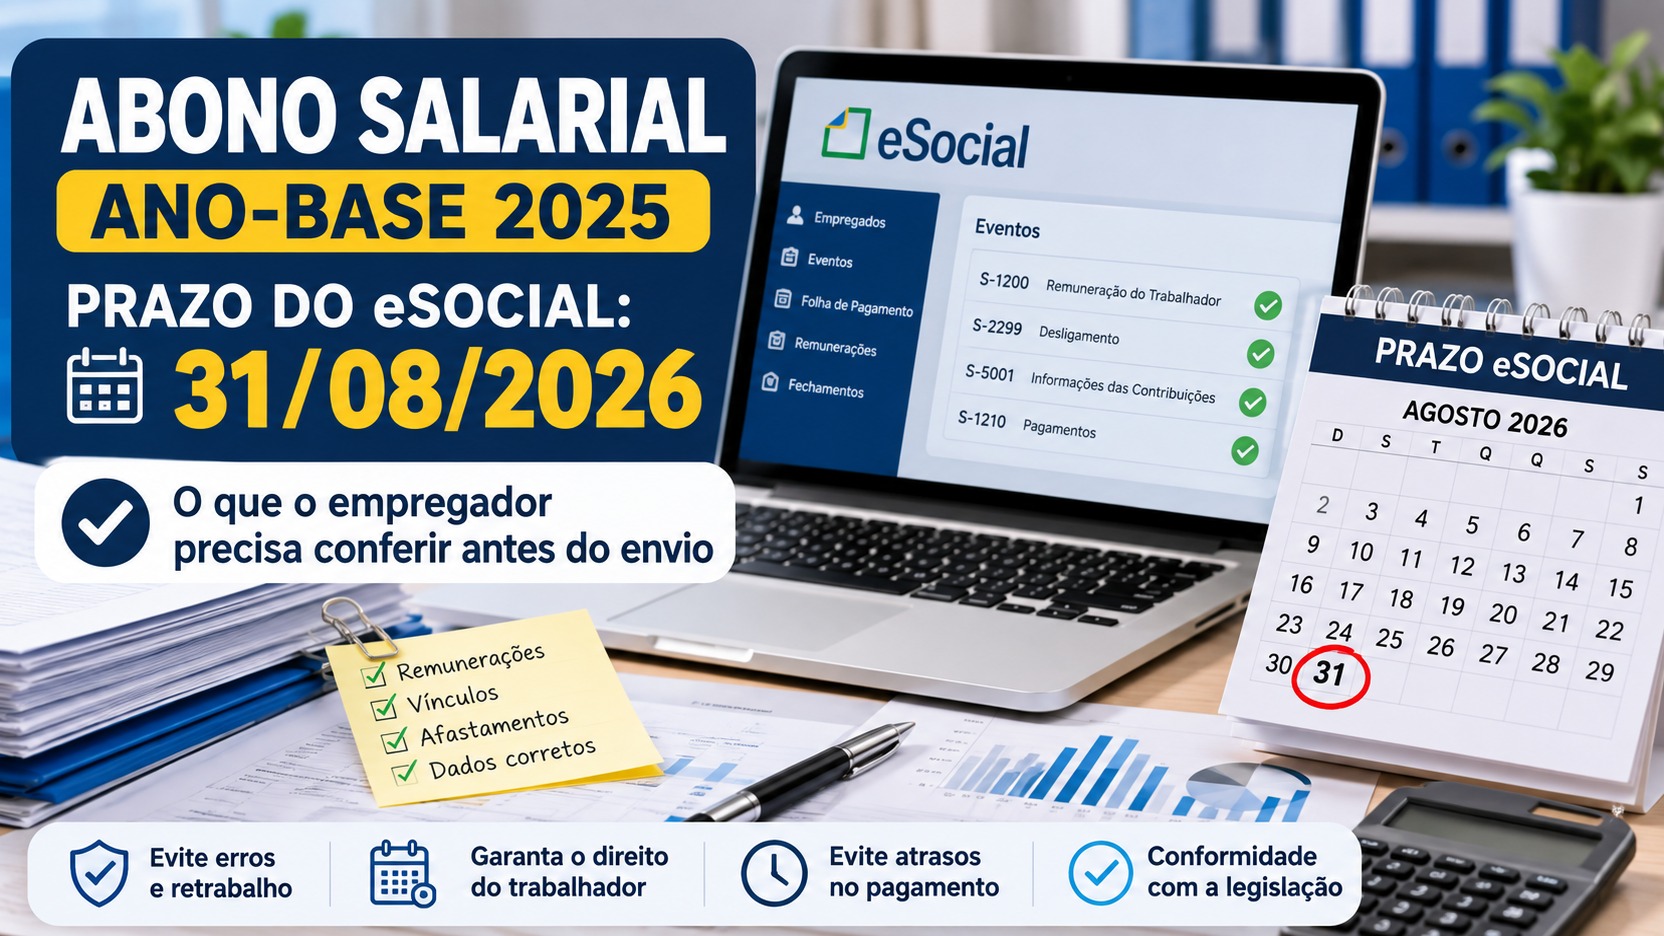
The deadline employers need to keep in mind for the 2025 base-year wage bonus is August 31, 2026. This is the cutoff date for the first processing of information submitted to eSocial. The Employer Guidance Manual from Brazil’s Ministry of Labor and Employment (MTE), updated in May 2026, uses the 2025 base year itself as an example: data submitted by 08/31/2026 enters the processing scheduled between October 2026 and January 2027, for the payment calendar that begins in February 2027.
The date should not be confused with June 20, 2026. MTE’s own manual associates 06/20/2026 with the second processing of the 2024 base year. For the 2025 base year, the second window runs through June 20, 2027. The distinction matters because moving a date by one year can lead HR to believe it has missed a deadline that is still open or, in the opposite direction, to postpone a correction that should enter the first processing round.
The correct timeline for the 2025 base year
Codefat/MTE Resolution No. 1,032, dated December 16, 2025, establishes that eligibility for the wage bonus is identified based on employment relationships and remuneration reported by employers in eSocial. The first cutoff considers information submitted by the last day of August in the year following the base year. Applied to 2025, that means August 31, 2026.
The MTE manual details the effect of this cutoff: 2025 base-year information submitted by 08/31/2026 will be processed between 10/01/2026 and 01/01/2027. Payment will follow the calendar beginning in February 2027, provided the worker meets the other eligibility requirements.
If the employer misses this first cutoff, there is still a second window. The Resolution provides for processing information submitted after the August deadline and through June 20 of the following year. The manual removes any doubt about how this rule applies in practice by stating that, for the 2025 base year, the date is 06/20/2027. In that case, processing is carried out for payment on October 15, 2027 or on the next business day.
After 06/20/2027, the information does not disappear and can still be reported, but it moves to the next processing calendar. In its 2025 base-year example, the manual states that payment begins in March 2028. The Resolution also establishes that, for information reported after this second cutoff, no administrative appeal may be filed for the purpose of bringing processing forward into a calendar that has already been missed.
Why the deadline is only part of the problem
Submitting something to eSocial before August 31 does not, by itself, guarantee that the worker will be identified correctly. Since the 2023 base year, wage bonus assessment has used eSocial data for private companies and public entities. MTE emphasizes that identification depends on employment relationships and remuneration, and that the nature assigned to payroll items is decisive for the average remuneration used for the benefit.
For that reason, year-end preparation for the wage bonus should not be treated as a simple receipt or submission-protocol check. The goal is to verify whether the information available for processing accurately represents the employment relationship, reporting periods and payments for the 2025 base year.
What to review before August 31, 2026
Employment relationship and hiring dates
The MTE manual cites as a recurring problem situations in which the hiring date was reported but remuneration was not submitted. It also mentions cases in which a preliminary admission is transmitted within the deadline, but the final admission is not sent or only arrives after the cutoff.
In practice, HR should confirm that every worker who had an employment relationship in 2025 has a properly finalized admission in eSocial and that the employment information matches the period actually worked. An existing admission without remuneration for the relevant reporting periods does not provide the processing system with the full set of data the wage bonus requires.
Remuneration for all relevant reporting periods
Identification takes into account remuneration reported by the employer. MTE warns about correctly reported admissions accompanied by missing remuneration or remuneration submitted after the deadline. The review should therefore compare the internal payroll with what was actually transmitted to eSocial throughout 2025.
The key issue is not simply whether payroll was closed. It is to verify whether the reporting periods in which work occurred have the appropriate remuneration tied to the correct employment relationship and whether later corrections also reached the remuneration event that will be read during wage bonus processing.
Classification of payroll items
The manual devotes several sections to payroll-item configuration because an incorrect classification can change the worker’s average remuneration. Codefat/MTE Resolution No. 1,032/2025 determines which amounts are included and which are excluded from the calculation. Excluded amounts include the constitutional one-third vacation bonus, the thirteenth salary and other payments covered by the legal situations cited in the rule.
This means the 2025 base-year review must look beyond the payroll total. The employer should verify that the internal code for each payment was linked to the correct eSocial classification for the reporting period in which it was used. MTE itself presents cases in which earnings were associated with inappropriate payroll items, causing remuneration to disappear or be distorted for wage bonus purposes.
Vacation pay and the constitutional one-third bonus
Vacation payments deserve specific attention because the manual records classification problems that alter average remuneration. For 2025 base-year reporting periods, the review must respect the table and validity dates of payroll-item classifications in force during that period, without retroactively applying a configuration created for later reporting periods.
The practical point is to correctly separate vacation remuneration from amounts that the rule excludes from the wage bonus calculation, especially the constitutional one-third vacation bonus. A misclassified payroll item can artificially increase the average or produce another improper effect on eligibility identification.
Corrections that require payroll resubmission
One of the manual’s most useful warnings is that correcting the classification of a payroll item in the table is not enough when that information has already been used in a payroll submission. If the change affects remuneration items, the remuneration events must be resubmitted so the data are updated and can participate in a new processing round.
The same reasoning applies to corrections for earlier reporting periods. MTE cites situations in which the employer corrects the registration number or payroll item but does not resubmit payroll. In those cases, the isolated registration correction may not reach the data set used to identify wage bonus eligibility.
Correct registration number when there is more than one employment relationship
When the same worker has more than one employment relationship at an establishment, the manual instructs employers to pay special attention to the registration number used in periodic events. A common mistake is using the registration number of an already terminated relationship to report remuneration for an active one.
Transfers between branches or CNPJs in the same economic group also require consistent registration numbers. Before the cutoff, it is worth comparing employment relationship, registration number, establishment and remuneration periods, especially for rehired or transferred employees or those with more than one contract during 2025.
Retroactive amounts and the correct reference period
Retroactive payments can distort the monthly average if they are concentrated in the month of payment instead of being assigned to the reporting periods to which they relate. The manual cites the infoPerAnt group in event S-1200 as a way to break down amounts by reference period, for example in adjustments arising from a collective bargaining agreement.
For the wage bonus, the distinction matters because the system needs to allocate remuneration to the correct month. If the entire retroactive amount is reported in a single period without the required breakdown, the average used for identification can become artificially high or low. If
there is an error, MTE instructs the employer to correct and resubmit the remuneration data.
Deletions, duplicates and changes made after submission
The manual also points to scenarios in which a company submits data within the deadline and later deletes the information, makes a contractual change after the deadline or duplicates events between headquarters and a branch. The fact that an event existed at some point does not mean it will remain valid at the cutoff used for processing.
That is why the final review should look at the current state of the information in eSocial, not only historical transmission receipts. What matters for processing is the set of employment relationships and remuneration that will be available and consistent when MTE captures the data.
CPF and registration consistency can also block payment
Codefat/MTE Resolution No. 1,032/2025 provides for data validation against government databases. Situations that may suspend payment include a CPF that is inconsistent, suspended, canceled, void or nonexistent in the Federal Revenue Service database, as well as inconsistencies in the information provided.
This does not make the employer responsible for resolving every registration issue belonging to the worker, but it reinforces the need to avoid discrepancies created by the employer’s own registration data or by the reported employment relationship. When HR identifies an identification inconsistency, the best time to address the source of the data is before the cutoff, not after the worker appears as ineligible.
What June 20, 2026 really means
The date confusion becomes easier to understand when the base years are separated. For the 2024 base year, the manual states that a second processing round covers new or corrected information submitted by 06/20/2026, with payment on 10/15/2026. That deadline is not the main cutoff for the 2025 base year.
For the 2025 base year, the correct sequence is different: first cutoff on 08/31/2026; processing between October 2026 and January 2027; regular payment calendar beginning in February 2027; second window through 06/20/2027; and payment from that second round in October 2027.
This distinction also explains why a page that merely repeats “June 20” without identifying the base year can mislead an employer. The deadline must always be read together with the base year and the processing round to which it refers.
A practical way for HR to wrap up the review
Before considering the matter closed, the employer can work by exception. First, identify workers who had an employment relationship in 2025 and verify that admission, termination where applicable, registration number and establishment are consistent. Then compare remuneration by reporting period with internal payroll and locate periods with no amount, amounts reported under a terminated registration number or events that were deleted.
Next, it is worth focusing the review on payroll items most likely to change the wage bonus average, such as salary, vacation pay, the constitutional one-third vacation bonus, bonuses, awards and retroactive payments. When a configuration has changed, the team needs to verify whether the affected payroll was actually resubmitted. For retroactive amounts, the correct
reference period also needs to be confirmed.
Finally, the transmission date should be treated as part of the control process. A technically perfect correction submitted after the cutoff enters a different round. For the 2025 base year, arriving by 08/31/2026 allows the case to participate in the first processing round; arriving after that date and through 06/20/2027 moves it to the October 2027 payment.
Missing August 31 does not erase the information, but it changes the calendar
The most important point for HR and employers is to separate the duty to correct information from the processing calendar. The first deadline is August 31, 2026. Employers that cannot leave the 2025 base-year data correct by that date may still submit or correct information through June 20, 2027 for the second round, but the worker will not follow the regular flow that begins in February 2027.
After June 20, 2027, the consequence is greater: the information will be processed in the next calendar. The Resolution also provides for a fine for an employer that fails to provide the information in the required form and within the established deadline, submits a false or inaccurate declaration, or omits information, under the legislation cited by the rule itself.
The safest reference for this closing review is the Employer Guidance Manual for the Wage Bonus, published by Brazil’s Ministry of Labor and Employment, together with Codefat/MTE Resolution No. 1,032/2025 and the current eSocial documentation. For the 2025 base year, the operational message is straightforward: 08/31/2026 is the main cutoff, and the quality of the submitted data is just as important as meeting the date.