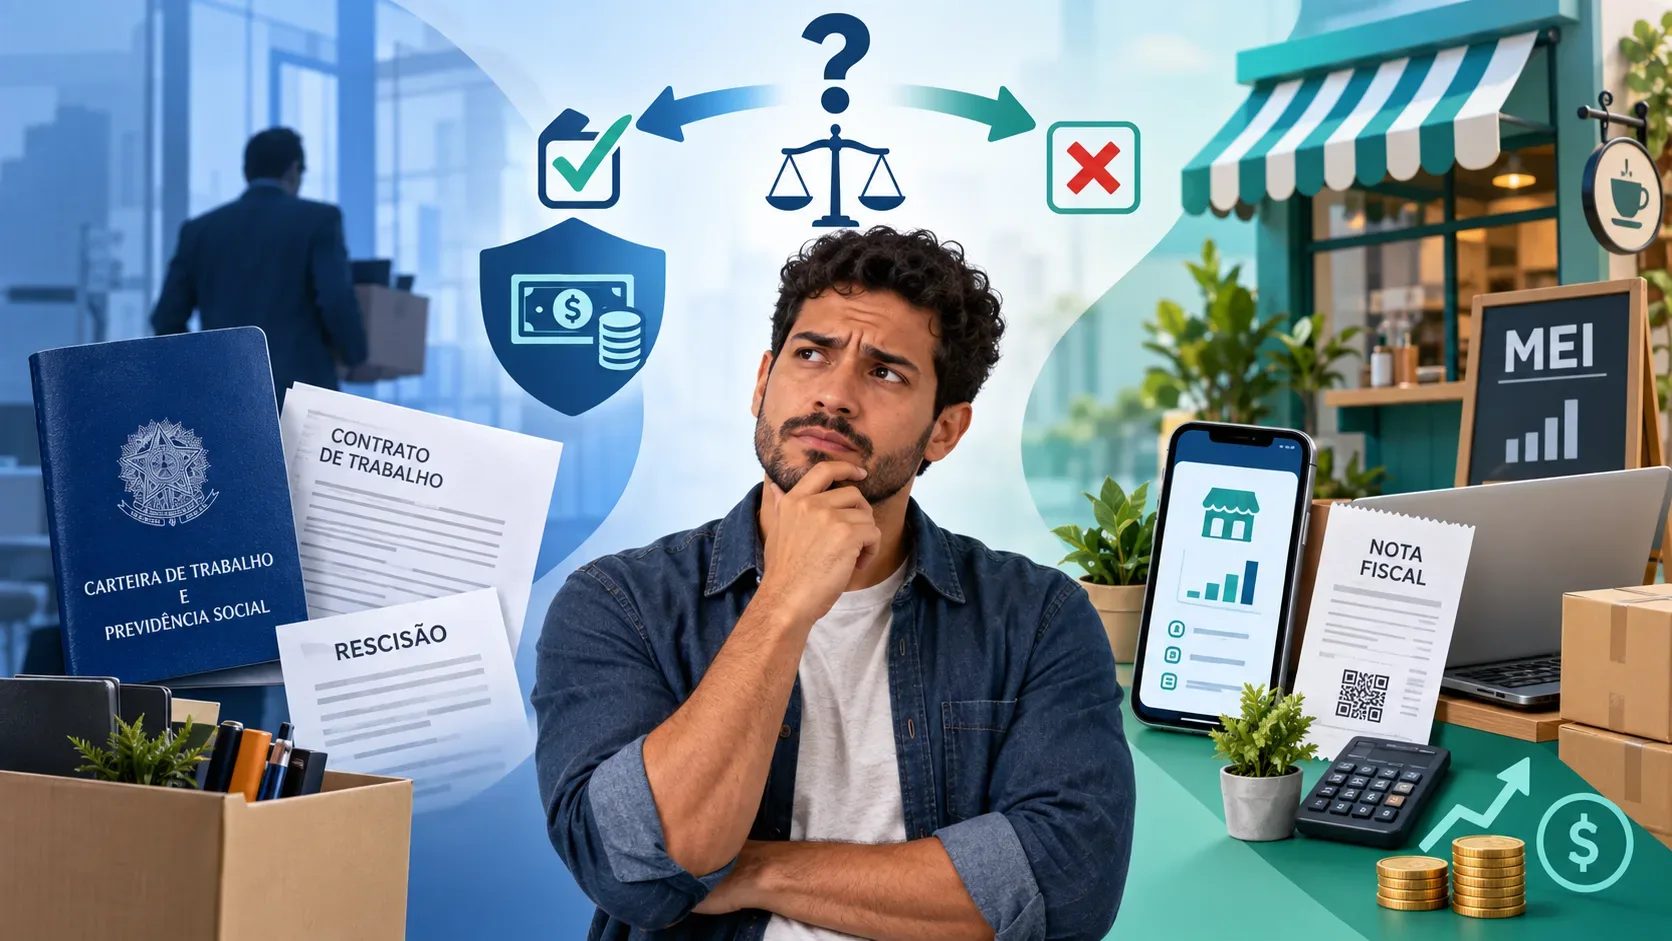
Having an active MEI does not automatically prevent a worker from receiving Brazilian unemployment insurance after dismissal without cause. The central rule is different: the worker must meet the benefit's requirements and must not have sufficient income of their own to support themselves and their family. Law No. 7,998/1990 also expressly states that registration as an Individual Microentrepreneur (MEI) does not, by itself, prove sufficient own income; that situation may be demonstrated through the MEI's simplified annual return.
In practice, two people with a MEI tax ID can receive different decisions. A registered business with no revenue, occasional activity and a business that generates sufficient income are not equivalent situations. Brazil's official Entrepreneur Portal states that when the MEI has had revenue through the business, entitlement to unemployment insurance is assessed case by case.
Which unemployment-insurance requirements still apply if you are also a MEI?
Being a MEI does not replace the general eligibility requirements for unemployment insurance for formal employees. According to the federal government's official service and Law No. 7,998/1990, the worker must have been dismissed without cause, must meet the minimum salary-history requirement for the relevant claim, must not be receiving an incompatible continuous social-security benefit, and must not have sufficient own income to support themselves and their family.
- First claim: salaries received for at least 12 months within the 18 months immediately preceding dismissal.
- Second claim: salaries received for at least 9 months within the 12 months immediately preceding dismissal.
- Third or later claim: salaries received in each of the 6 months immediately preceding dismissal.
These criteria are available in the official Apply for Unemployment Insurance service and in the consolidated text of Law No. 7,998/1990.
An active MEI, by itself, is not proof of sufficient income
The most important point for avoiding a wrong conclusion is in paragraph 4 of Article 3 of Law No. 7,998/1990: registration as a MEI does not prove sufficient own income to support the family, except when that condition is demonstrated in the individual microenterprise's simplified annual return.
The specific guidance on the Entrepreneur Portal reinforces this interpretation: a person who is a MEI and also held a registered employment relationship may be entitled to unemployment insurance if the legal requirements are met. Therefore, the existence of a MEI registration is not an automatic “yes” or “no” rule.
See the official guidance on MEI, registered employment and unemployment insurance.
What changes if the MEI had business revenue?
When there has been business revenue, the assessment depends more heavily on the specific circumstances. The Entrepreneur Portal states that a MEI will not be entitled to unemployment insurance if sufficient own income to support the family is demonstrated, and that the assessment is made case by case.
It is also important to understand what the DASN-SIMEI annual return records. The annual return reports the MEI's annual gross revenue, not the business's profit. The official DASN-SIMEI service also explains that a MEI with no revenue must still file the return, reporting zero values.
For that reason, it is not safe to turn one fact — “has a business registration”, “issued an invoice” or “had some revenue” — into a definitive conclusion about the benefit. The legally relevant criterion is whether there is sufficient own income, and the administrative guidance provides for an assessment of the individual case.
See the official sources on MEI revenue and unemployment insurance and the DASN-SIMEI annual return.
Common scenarios: what each situation suggests
| Situation | What it indicates | What still needs to be checked |
|---|---|---|
| Active MEI with no revenue | The business registration alone does not prove sufficient income. The DASN-SIMEI may report gross revenue of zero. | All other unemployment-insurance requirements and the administrative assessment. |
| MEI with low or occasional revenue | There is no automatic answer based only on the existence of revenue. | Whether there is sufficient own income to support the worker and their family, as assessed in the case. |
| MEI with sufficient own income | The requirement of not having sufficient own income is not met. | How that condition appears in the data and documents considered in the assessment. |
| Person was only a MEI and closed the business | Closing the MEI does not, by itself, create entitlement to unemployment insurance. | The formal-worker benefit presupposes involuntary unemployment arising from an employment relationship covered by the rules. |
| CLT employee resigned or was dismissed for cause | This does not match the dismissal without cause required for standard formal-worker unemployment insurance. | Whether any different, specific legal situation applies to the individual case. |
The Entrepreneur Portal also clarifies that a person who was only a MEI, with no employment relationship, does not become entitled to unemployment insurance simply by closing the business registration. See the official guidance for people who are only MEIs.
Which MEI documents are worth organizing?
There is no single list of MEI documents that is mandatory in every claim. If there is a block, notification or need for an administrative appeal, the official process indicates which documentation is required. Even so, it is prudent to keep records that show the business's real economic activity organized, because they may help explain the situation if requested.
- DASN-SIMEI and filing receipt: show the annual gross revenue declared.
- Monthly Gross Revenue Report: helps organize and substantiate amounts received month by month.
- Invoices and revenue records: support the MEI's revenue records.
- CLT employment and termination documents: remain relevant to the unemployment-insurance claim as a formal employee.
The government provides a MEI Monthly Gross Revenue Report service, describing the document as a tool for organizing and substantiating the monthly amounts received from the business activity.
How to apply without assuming that the MEI will cause a denial
If the dismissal was without cause and the other requirements appear to be met, the appropriate route is to submit the claim through the official channels. Official service pages state that formal workers may apply from the 7th day after dismissal and within up to 120 days.
- Check the termination data and the unemployment-insurance claim number.
- Submit the application through gov.br or the digital channels indicated by the Ministry of Labour and Employment.
- Monitor notifications on the claim.
- If a block related to income, business activity or registration appears, read the stated reason before concluding that the MEI eliminated your entitlement.
- When an administrative appeal is available, submit the explanation and the documents requested by the system.
The official unemployment-insurance appeal service states that a review can be filed through the portal or the Digital Work Card app and that the documentation required is indicated during the filing process.
Three mistakes that can lead to a poor decision
1. Closing the MEI only to “guarantee” unemployment insurance
Closing the business registration does not, by itself, create an entitlement that did not exist. What matters is whether the situation meets the legal requirements. If the person was only a MEI, closing the registration does not turn business activity into an employment relationship or a dismissal without cause.
2. Confusing revenue with profit or disposable income
The DASN-SIMEI reports annual gross revenue. This does not mean that all revenue is profit. At the same time, existing revenue should not be omitted: the information must be consistent with the declarations and documents submitted.
3. Assuming that any MEI status is incompatible with the benefit
The law itself rejects that automatic presumption. MEI registration alone is not proof of sufficient own income. The decision depends on the unemployment-insurance requirements and the economic situation demonstrated.
Checklist before applying
- Was the CLT employment terminated without cause?
- Do you meet the minimum salary-history requirement for this claim?
- Are you receiving any incompatible continuous social-security benefit?
- Did the MEI have gross revenue in the relevant period?
- Does the business generate sufficient own income to support you and your family?
- Are the DASN-SIMEI and monthly revenue records consistent and available?
- If the claim generates a notification, can you document your situation?
In short: MEI status and CLT employment can coexist, and a dismissal without cause may lead to unemployment-insurance entitlement even with an active business registration. The decisive point is not simply “having a MEI”, but meeting the general requirements and not having sufficient own income to support yourself and your family. Because the assessment of MEI revenue can be individualized, cases involving doubt, denial or inconsistent documents deserve human review and, where necessary, direct guidance from the Ministry of Labour and Employment.
This content is for general information and does not replace individual legal or administrative advice. Operational rules and service channels can change; always check the notification on your claim and the current official guidance.