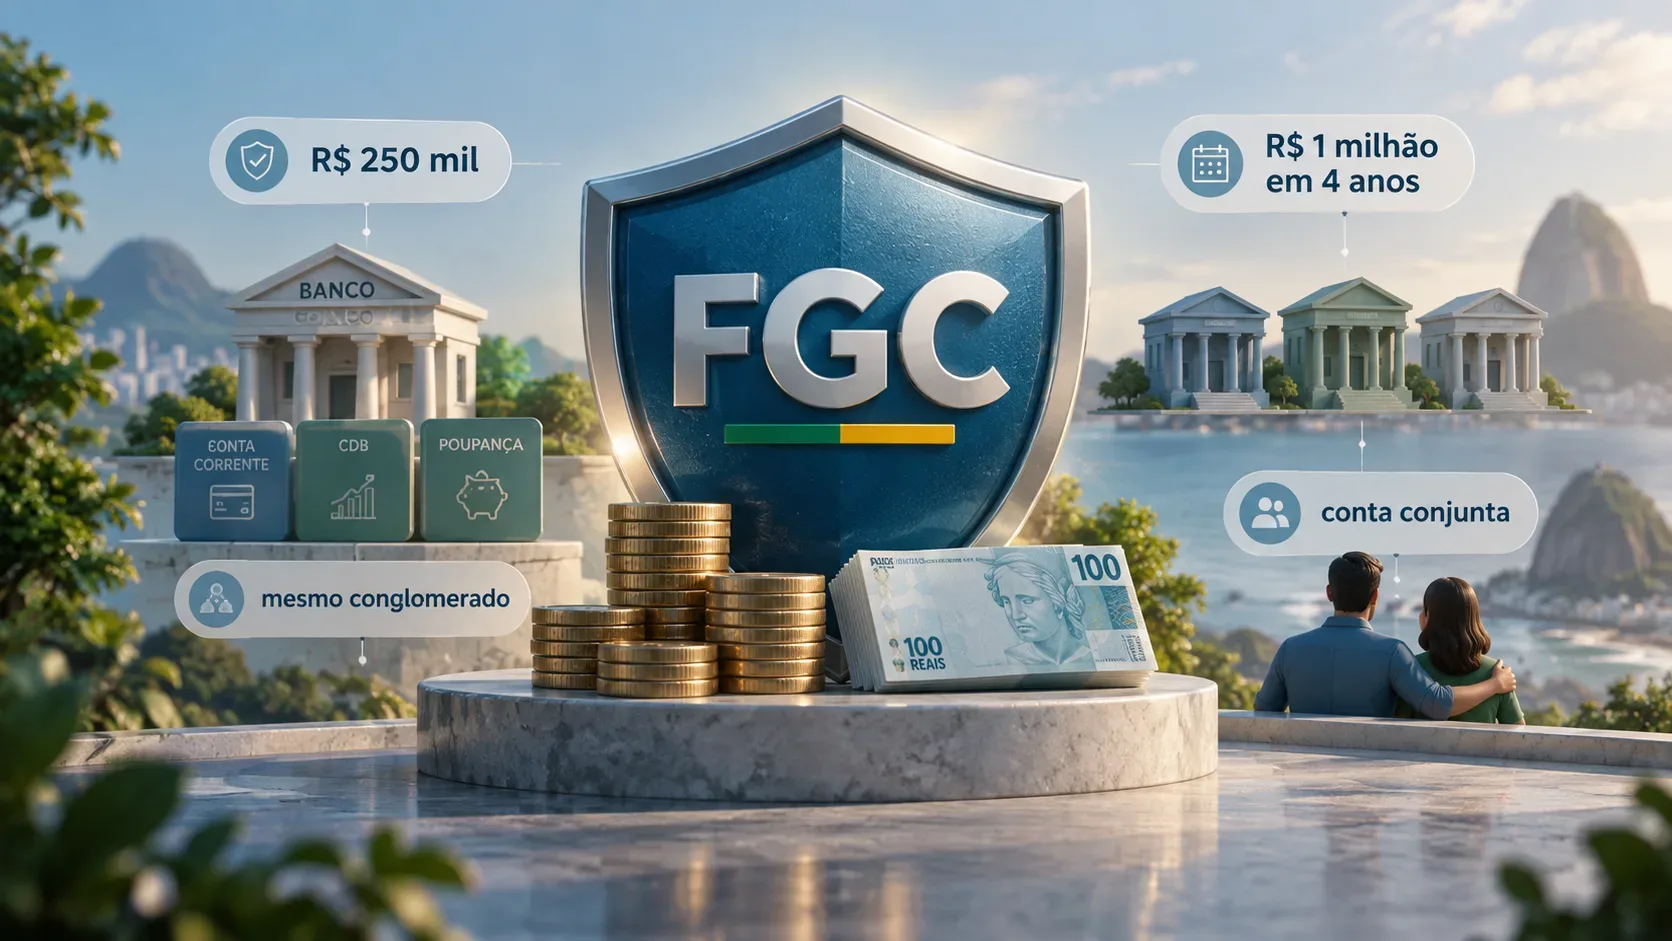
The R$250,000 limit of Brazil's Fundo Garantidor de Créditos, or FGC, is not a limit per account or per product. Under the ordinary guarantee, it applies per CPF or CNPJ against the same associated financial institution or against all institutions in the same financial conglomerate. There is also a global cap of R$1 million in guarantees paid to the same CPF or CNPJ within a four-year period, under the conditions established by the FGC.
In practice, calculating protection requires four questions: who owns the credit, what covered balance exists on the special-regime date, which institutions belong to the same conglomerate, and how much the FGC has already paid to that CPF or CNPJ within the four-year window.
What the R$250,000 limit actually limits
The FGC states that the total credits of one person against an associated institution, or against all associated institutions in the same financial conglomerate, are guaranteed up to R$250,000. This means that opening several accounts or buying several covered products within the same conglomerate does not automatically multiply the guarantee.
For this calculation, the relevant balance includes principal and earnings accrued up to the date on which the Central Bank places the institution under a special regime, such as intervention or liquidation. If the covered balance exceeds R$250,000, the excess is not paid under the ordinary guarantee and remains as a residual claim to be handled in the institution's proceeding.
The official starting points are the FGC page Sobre a garantia FGC and the FGC FAQ.
Before adding balances, find out whether the banks belong to the same conglomerate
A commercial brand name is not enough to conclude that there are separate limits. Two different institutions may belong to the same conglomerate and, in that case, covered credits held by the same CPF or CNPJ are added together for the R$250,000 cap.
The FGC maintains an official page of associated institutions and conglomerates. Checking it is important before spreading investments with the goal of reducing concentration risk.
A practical formula for checking coverage
For each CPF or CNPJ, calculate coverage in three layers:
- Add the balances of covered products within each institution or conglomerate. Include principal plus earnings up to the special-regime reference date.
- Apply the R$250,000 limit to the total for each institution or conglomerate. Any excess is outside the ordinary guarantee for that event.
- Check the R$1 million global cap over four years. Guarantee payments inside the window reduce the remaining global amount available for later events.
Four numerical scenarios
| Scenario | Amounts | Practical result |
|---|---|---|
| One bank | R$270,000 covered balance | Up to R$250,000 falls under the ordinary guarantee. R$20,000 remains as a residual claim. |
| Same conglomerate | R$140,000 at Bank A and R$160,000 at Bank B in the same group | The R$300,000 balances are aggregated. The ordinary guarantee is capped at R$250,000. |
| Different banks | Four R$250,000 guarantee payments at independent institutions within the same four-year window | Total payments reach R$1 million. A new event subject to the same cap may produce no additional payment until the cap is restored. |
| Joint account | R$300,000 balance with two holders | The account guarantee is capped at R$250,000 and split equally: R$125,000 for each holder. |
Scenario 1: R$270,000 in a single bank
Consider a CDB whose balance, including earnings on the liquidation date, is R$270,000. Even if the original principal was below R$250,000, the limit looks at the relevant balance on the reference date. Therefore, up to R$250,000 may be covered by the ordinary guarantee, while the remaining R$20,000 stays outside that payment.
For products subject to tax, the FGC explains that applicable taxes are withheld according to current law. Therefore, R$250,000 is a gross guarantee limit and does not necessarily mean that R$250,000 net will be deposited in the creditor's account.
Scenario 2: R$140,000 in one bank and R$160,000 in another bank from the same conglomerate
If Banks A and B belong to the same conglomerate, the balances of the same holder are aggregated. In this example, R$140,000 plus R$160,000 equals R$300,000. Two brands or two accounts do not create two R$250,000 limits.
The maximum ordinary guarantee for that CPF or CNPJ, considering the conglomerate, remains R$250,000. The R$50,000 excess is not protected by the ordinary guarantee for that conglomerate.
Scenario 3: independent institutions and the R$1 million four-year cap
The R$250,000 limit per institution or conglomerate exists alongside a second limit. For operations covered by the global-cap rule, the FGC limits total guarantees paid to the same CPF or CNPJ to R$1 million within a four-year period.
Suppose that within one window four independent institutions are liquidated and the investor is entitled to R$250,000 from each. The payments would total R$1 million. After that, a new event inside the same window may find the global cap exhausted.
The count starts on the date of the first intervention or liquidation that generates a guarantee under this rule. The FGC states that after the four-year period the maximum amount is restored. The global-cap rule applies to transactions entered into or renegotiated from December 22, 2017 onward.
Scenario 4: a joint account with a R$300,000 balance
A joint account does not create R$250,000 of coverage for each holder on that same account. First, the account itself is subject to a limit of R$250,000 or the account balance, if lower. That amount is then divided equally among the holders.
With two holders and a R$300,000 balance, the maximum guaranteed amount for the account is R$250,000. Each holder receives R$125,000. With three holders, the split of that limit would be approximately R$83,333.33 per person.
The FGC also applies the maximum per CPF to the total portions that the same person receives across several joint accounts at the institution. In addition, the R$1 million four-year global cap is tracked individually by CPF. Thus, in the example where two holders each receive R$125,000, each person's remaining global amount is separately reduced by R$125,000 within the applicable window.
Which products are covered by the ordinary guarantee
Products listed by the FGC as guaranteed include:
- checking-account deposits and savings deposits;
- CDB and RDB time deposits;
- LCI and LCA;
- LCD, the Development Credit Note;
- LC, or bills of exchange;
- LH, or mortgage notes;
- salary accounts and other non-checkable deposits covered by regulation;
- certain repurchase agreements backed by securities issued after March 8, 2012 by a related company.
The fact that a product is sold by a bank does not, by itself, mean that it is covered by the FGC. Coverage depends on the type of credit and the Fund's rules.
What is outside FGC coverage
Examples of products and credits without ordinary FGC coverage include Tesouro Direto and other government securities, investment funds, debentures, CRI, CRA, LIG, LI, LF, capitalization bonds, deposits abroad, and judicial deposits. Stocks and cryptoassets also do not acquire FGC coverage simply because they are purchased through a financial institution.
Private pension products such as PGBL and VGBL are also not covered by the FGC. The Fund's FAQ clarifies that these structures are outside the ordinary guarantee.
The FGC does not eliminate credit risk or replace diversification
The guarantee reduces the impact of an intervention or liquidation for eligible credits within the limits, but it does not make every investment risk free. Amounts above the caps may remain exposed, uncovered products remain outside the mechanism, and payment depends on the process that starts after the special regime is declared.
It is also important to distinguish the ordinary guarantee from the DPGE, a special guaranteed time deposit. DPGE follows its own rules and limits and should not be used to interpret ordinary coverage for CDB, LCI, LCA, savings, or checking accounts.
Checklist for calculating your coverage before investing
- Confirm that the product is on the FGC list of guaranteed credits.
- Confirm that the institution is associated with the Fund.
- Check whether other institutions in your portfolio belong to the same conglomerate.
- Add principal and projected earnings with enough margin to avoid unknowingly exceeding the R$250,000 limit.
- For joint accounts, calculate the account limit first and then split it among holders.
- If you have received an FGC guarantee in the last four years, check how much remains under the R$1 million global cap.
- Do not confuse covered banking products with funds, government securities, or private securities that are outside the ordinary guarantee.
In short, the right question is not simply "do I have less than R$250,000 in this investment?" The calculation must consider all covered credits held by the same owner in the same conglomerate, the split of joint accounts, and the history of guarantees paid within the four-year window.