The grace period is the interval during which a person may keep insured status under Brazil's General Social Security Regime, RGPS, even without making contributions. For someone who leaves work that created mandatory affiliation with the INSS, the most common reference is 12 months. This can reach 24 months when the person has made more than 120 monthly contributions without an interruption that caused loss of insured status, and it may receive another 12 months when unemployment is proven under the INSS administrative rules. When both extensions validly apply, the period can therefore reach 36 months.
Those numbers are starting points, not automatic end dates. The insured category, the last valid contribution month, a recently terminated benefit, the contribution history and evidence of unemployment all affect the analysis. In addition, the formal loss of insured status occurs later than the simple end of the stated number of grace-period months. The right question is therefore not only “how many months do I have?” but “which rule applies to my case and from what date should the period be counted?”.
What it means to keep INSS insured status
Insured status is the condition that keeps a person linked to RGPS social security protection. While there is valid affiliation and regular contributions, that condition is normally maintained. When contributions or covered work stop, legislation preserves the status for certain periods known as the grace period.
During that interval, the insured person keeps the rights attached to insured status. This does not mean that every benefit is granted automatically. Each benefit still has its own requirements, such as a qualifying contribution period, incapacity, dependency or the occurrence of the insured event. Law No. 8,213/1991, article 15, and INSS Normative Instruction No. 128/2022, updated on May 21, 2026, regulate the maintenance and loss of insured status.
How long the grace period lasts in each situation
| Situation | Basic period of insured status | Main point |
|---|---|---|
| Mandatory insured person who stops covered paid work or stops contributions | Up to 12 months | The period may be extended to 24 or 36 months when the additional requirements are met. |
| Voluntary insured person who stops contributing | Up to 6 months | The six-month rule is specific to voluntary insured persons. A special rule protects someone who was previously mandatorily insured and became voluntary during an earlier grace period if the previous status is more favorable. |
| Insured person after the termination of an incapacity benefit or maternity benefit | Up to 12 months | The period begins after the benefit ends, under the INSS counting rules. |
| Person affected by a disease requiring compulsory isolation | Up to 12 months after isolation ends | A specific statutory situation. |
| Detained or imprisoned insured person | Up to 12 months after release | The person must have had insured status before imprisonment for protection to be assessed on this basis. |
| Insured person incorporated into the Armed Forces for military service | Up to 3 months after discharge | A specific period provided by article 15 of Law No. 8,213/1991. |
| Insured person receiving a benefit that preserves insured status | No time limit while the benefit lasts | The law excludes accident allowance from this rule. INSS regulations also treat the legacy supplementary allowance as an exception. |
The official INSS page on insured status summarizes these situations and highlights the 6, 12, 24 and 36-month periods depending on the case.
When 12 months can become 24 months
The mandatory insured person's 12-month period receives another 12 months when the person has already paid more than 120 monthly contributions without an interruption that caused loss of insured status. The statutory wording is “more than 120”, so the contribution history must exceed 120 monthly contributions for this specific extension.
The current administrative rule adds an important nuance: after this extension has been used, it becomes available again on a later occasion only when the person completes 120 new monthly contributions without losing insured status. This prevents the extension from being treated as a permanent bonus that automatically applies to every later period without contributions.
When the period can reach 36 months
In addition to the contribution-history extension, an unemployed insured person may receive another 12 months. Under the current INSS administrative rule, unemployment must be proven by registration with Brazil's National Employment System, SINE, or by receipt of unemployment insurance during the period in which insured status is still maintained, provided there is no information that contradicts that condition.
A mandatorily insured person with the basic 12-month period may therefore reach 24 months through the unemployment extension. If the person also satisfies the rule of more than 120 monthly contributions without loss of insured status, the two extensions may be combined and the period can reach 36 months.
The current Normative Instruction also expressly states that an individual contributor may qualify for the unemployment extension. The analysis still depends on proof of unemployment and the absence of incompatible facts, such as starting new paid work. Beginning paid activity, or receiving an incapacity or maternity benefit, can end the extension based on unemployment.
Voluntary insured persons: why the normal period is 6 months
A voluntary insured person is someone who joins the RGPS without performing activity that creates mandatory affiliation, provided the legal conditions for that category are met. When voluntary contributions stop, the basic period for maintaining insured status is up to 6 months.
There is an important transition rule. If a mandatorily insured person was already within a 12, 24 or 36-month grace period and started contributing as voluntary during that interval, after those voluntary contributions stop the person may use the grace period from the previous status when it is more favorable. It is therefore unsafe to look only at the last category recorded without reconstructing the sequence of work relationships and contributions.
What happens when a benefit ends
While a person receives a social security benefit that preserves insured status, that status is maintained without a time limit for as long as the benefit lasts. The best-known statutory exception is accident allowance. When an incapacity benefit or maternity benefit ends, INSS regulations provide for up to 12 months of continued insured status, subject to the applicable counting rules.
This matters especially for someone whose temporary incapacity benefit has just ended, whose permanent incapacity retirement has been terminated, or whose maternity benefit has ended. The starting point for the grace period may be the termination of the benefit rather than the last contribution made before the benefit began.
How INSS counts the period in practice
INSS Normative Instruction No. 128 provides that, in the relevant situations, the maintenance period is counted from the first day of the month following the event that starts the count. When contributions stop, the rule considers the last contribution month in which the contribution salary is equal to or above the required minimum, subject to permitted adjustments such as supplementation or grouping when applicable.
This means it is not enough to take the date of the last payment and simply add 12, 24 or 36 months. The legislation itself provides that loss of insured status occurs on the day after the end of the deadline for paying the contribution relating to the month immediately following the end of the maintenance period. In practical terms, a contribution due-date stage sits between the end of the grace-period months and the formal loss date.
For that reason, calculations based only on a day count can produce the wrong date. For situations close to the limit, especially when a benefit claim or an insured event such as incapacity or death is involved, the exact milestone should be checked against the CNIS record and the current administrative rule.
Four examples for identifying the correct rule
1. Employee who stopped working and has no proven extension
If the person leaves work that made them mandatorily insured and does not satisfy an additional condition, the basic reference is up to 12 months. The exact loss date must be determined under the INSS counting rule rather than by simply adding 12 months to the last day worked.
2. Mandatory insured person with more than 120 contributions without loss of status
If there were more than 120 monthly contributions without an interruption that caused loss of insured status, the 12-month period may receive another 12 months and reach 24 months.
3. Insured person who also proves unemployment
If, in addition to having the contribution history required for 24 months, the person proves unemployment under the conditions accepted by INSS, another 12 months may be added, reaching 36 months. If the person does not qualify for the extension based on more than 120 contributions but does prove unemployment, the period may rise from 12 to 24 months.
4. Voluntary insured person who simply stopped contributing
For someone who was only in the voluntary insured category, the basic period is up to 6 months. Before concluding that this is the final period, however, it is necessary to check whether the person came from a previous mandatory insured status whose grace period may still be used because it is more favorable.
Does losing insured status erase earlier contributions?
No. Loss of insured status does not erase the contribution history recorded in the system. It affects protection that depends on maintaining that status and may change the requirements for certain benefits. The INSS regulation itself preserves situations in which loss of insured status does not prejudice retirement benefits for which all other requirements had already been met, as well as specific pension situations.
It is also important to distinguish insured status from the qualifying contribution period. Insured status is the condition of social security protection at a particular time. The qualifying period is the minimum number of contributions required for certain benefits. A person may have many old contributions and still lack insured status for a benefit that requires it. Conversely, losing insured status does not reset the entire contribution history to zero.
What to check in the CNIS before calculating your grace period
- the category in which you were affiliated before contributions stopped;
- the end date of the last employment relationship or the last valid contribution month;
- whether there was an incapacity or maternity benefit and its termination date;
- whether there are more than 120 monthly contributions without an interruption that caused loss of insured status;
- whether there is unemployment and documentation compatible with the current administrative rule;
- whether there was a new work relationship, paid activity or voluntary contribution during the period;
- whether there are contributions below the minimum that require adjustment to produce the expected social security effects.
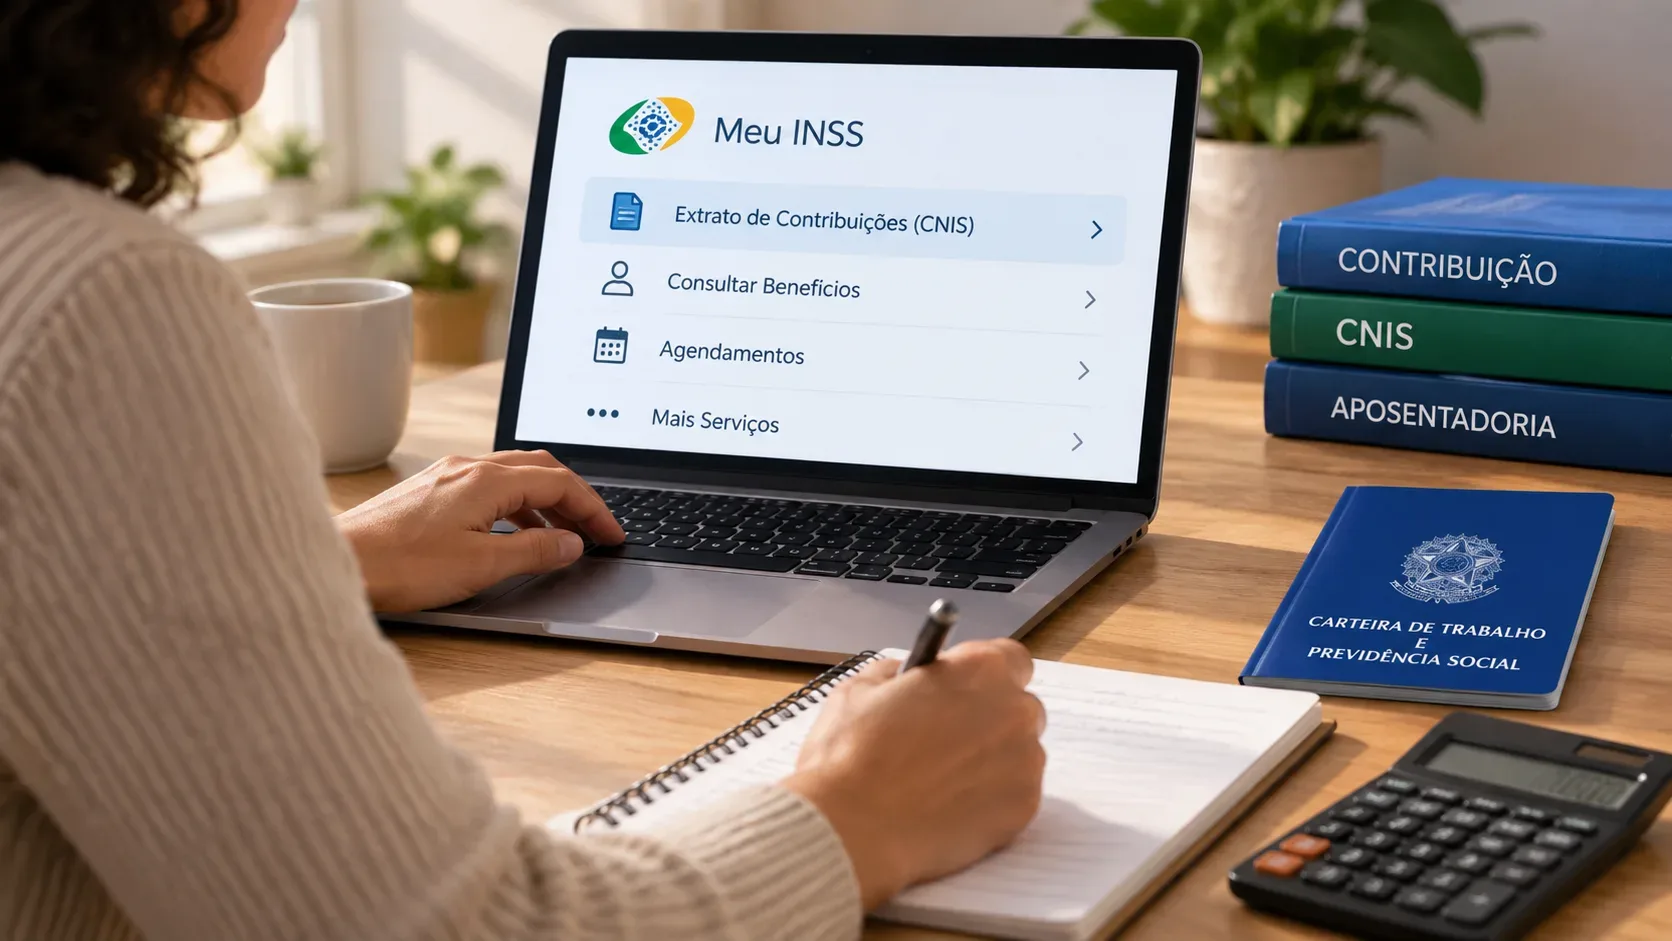
The official CNIS Contribution Statement service allows users to review employment relationships, earnings and social security contributions. The CNIS is the starting point for rebuilding the timeline, but registration discrepancies or special situations may require additional documentation.
A practical sequence for avoiding confusion between 12, 24 and 36 months
Use a sequence of questions. First, identify whether you were mandatorily or voluntarily insured. Second, determine which event started the count: end of covered work, end of contributions or termination of a benefit. Third, verify whether the basic period is 12 or 6 months. Fourth, for a mandatorily insured person, check whether there are more than 120 contributions without loss of insured status. Fifth, check whether unemployment is proven under INSS rules. Only then calculate the formal loss date under the contribution due-date rule.
In short, 12 months is the most common reference for someone leaving mandatory covered work, 24 months may result from one of the applicable extensions, and 36 months requires the combination of the relevant conditions. For voluntary insured persons, the basic reference is 6 months. The exact period depends on the person's actual timeline, so a reliable calculation must combine category, CNIS records, contribution history, terminated benefits and any applicable extensions.