A low interest rate in an ad does not guarantee that the contract will have the lowest cost. To compare loans and financing offers, it helps to separate four measures: the interest rate, the Custo Efetivo Total (CET), the installment amount, and the total amount paid. They are related, but they answer different questions.
Interest rate and CET do not measure the same thing
The interest rate is the price charged for using money over time. CET, by contrast, consolidates the charges and expenses linked to the transaction. Under rules issued by Brazil's National Monetary Council, the calculation considers the credit cash flows and may include interest, fees, taxes, insurance, and other expenses connected to the contract.
- Interest rate: shows the basic financial cost of the credit.
- CET: combines the transaction costs into an annual percentage rate.
- Installment: shows how much leaves the budget at each due date.
- Total amount: shows the sum paid over the life of the contract under the agreed terms.
CMN Resolution No. 4,881/2020 requires CET to be expressed as an annual percentage rate and disclosed before the contract is signed. The institution must also provide the calculation statement. The Central Bank of Brazil advises consumers to check CET because it adds the charges and expenses of the transaction and helps compare offers.
Why a lower rate can still produce a more expensive contract
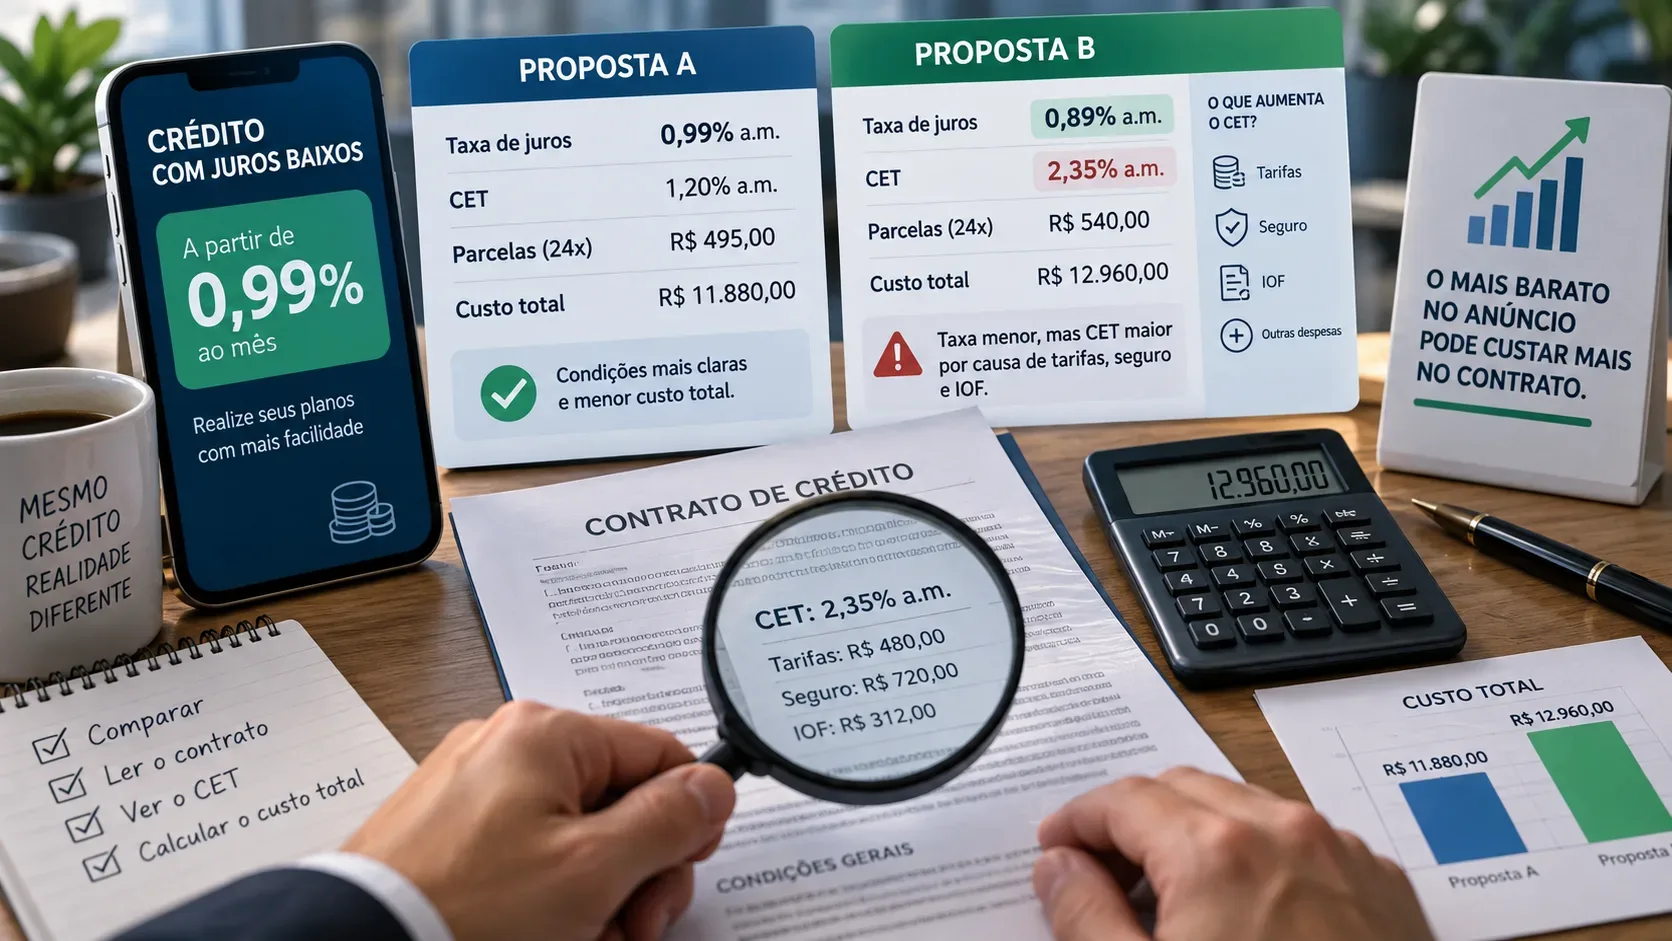
Two offers can have similar interest rates but very different additional costs. One may charge a fee, insurance, or other expenses that increase the financed amount or reduce the net amount actually received by the customer. IOF, when applicable, is also part of the cash flow considered in the cost of the transaction.
That is why the advertised rate can be lower while the annual CET and the total amount paid are higher. The key is to compare equivalent offers, with the same net credit amount and a similar term.
Two hypothetical comparison examples
Consider two offers for educational purposes only. In both, the borrower wants to receive R$ 10,000.00 net and repay it in 24 monthly installments. The extra costs in this example are financed together with the credit. The amounts below are hypothetical, do not represent a real offer, and use an approximate CET based on the simulated cash flows.
| Item | Offer A | Offer B |
|---|---|---|
| Net credit received | R$ 10,000.00 | R$ 10,000.00 |
| Advertised interest rate | 1.20% per month | 1.35% per month |
| Fee | R$ 600.00 | R$ 100.00 |
| Insurance | R$ 480.00 | R$ 0.00 |
| IOF in the example | R$ 200.00 | R$ 200.00 |
| Financed base | R$ 11,280.00 | R$ 10,300.00 |
| Approximate installment | 24 x R$ 543.72 | 24 x R$ 505.30 |
| Sum of installments | R$ 13,049.26 | R$ 12,127.32 |
| Approximate annual CET in the simulation | 31.07% per year | 21.36% per year |
Offer A advertises the lower interest rate, but the additional costs increase the financed base. In the hypothetical cash flow, it ends up with a higher installment, a higher total amount paid, and a higher annual CET. Offer B charges a slightly higher nominal interest rate, but has fewer additional expenses and, in this simulation, a lower consolidated cost.
In a real contract, disbursement dates, due dates, costs paid upfront or financed, and other details change the calculation. That is why the CET statement supplied by the institution should be used as the reference for the actual contract being offered.
How to compare two offers without getting lost in the numbers
- Use the same comparison base. Compare offers for the same net amount received and, preferably, the same term.
- Find the annual CET. Do not compare the monthly interest rate of one offer with the annual CET of another.
- Check the CET statement. Identify which fees, taxes, insurance charges, and other expenses are included in the cash flow.
- Compare the installment and the sum of installments. A lower installment may result from a longer term rather than cheaper credit.
- Check the amount actually disbursed. Costs deducted before disbursement can leave the customer with less than the nominal contract amount.
- Watch for variable components. Resolution No. 4,881 states that benchmarks that change during the contract, such as certain floating rates or price indexes, are not included in CET and must be disclosed in the statement.
Common traps when reading a credit offer
- Looking only at the advertised rate: it does not summarize fees, insurance, taxes, and other expenses.
- Looking only at the installment: a longer term can reduce the payment while increasing the total amount paid.
- Comparing percentages from different periods: monthly and annual rates are not directly comparable without proper conversion.
- Ignoring the net amount received: two offers with the same nominal amount can deliver different net amounts.
- Treating CET as a forecast for every scenario: it reflects the conditions used in the calculation. Late payments, penalties, or changes in variable benchmarks can alter what is actually paid.
What should be available before signing
For transactions covered by the rule, the institution must disclose CET before the contract is signed and provide the calculation statement with the cash flow components and the sum of installments. If the credit is contracted, the statement must be prominently included in the contract. The rule also requires CET information in advertising for covered transactions when interest rates are presented.
A simple way to remember it
Interest rate shows the basic financial cost. CET shows the consolidated transaction cost as an annual rate. Installment shows the recurring budget impact. Total amount shows how much leaves your pocket over the life of the contract. To compare similar offers, read all four figures together and review the CET statement before accepting the contract.