If you already know that you won't be able to pay the entire bill, the most useful decision takes place before the due date: finding out how much each item really costs and whether the installment fits without pushing the problem to the next month. The most common mistake is to compare only the smallest portion. Minimum payment, invoice installments and loans are different forms of credit, with different terms and costs, and are only comparable when you put CET, total amount payable, term and monthly disbursement on the same basis.
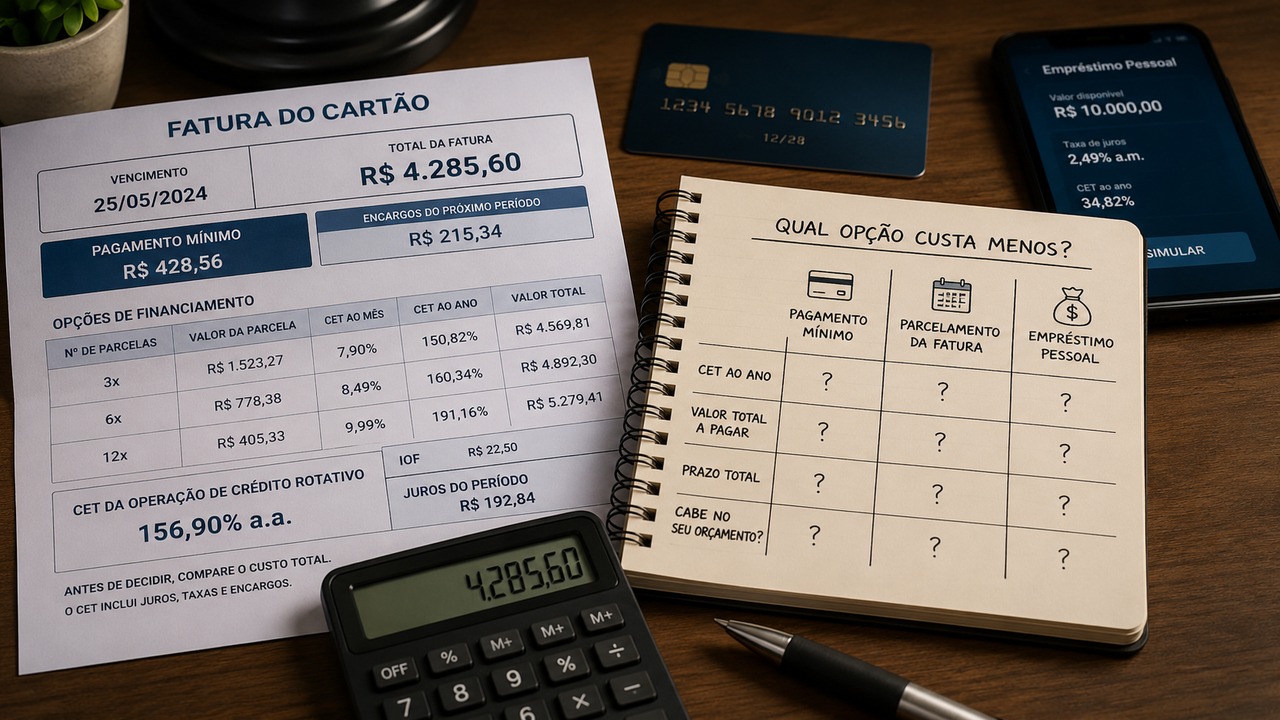
Since July 1, 2024, credit card invoices must include a specific area for payment alternatives. In it, the issuer must inform the minimum payment, the total value of the invoice, the charges for the following period if the customer only pays the minimum, the financing options for the outstanding balance in ascending order of total amount payable, the effective monthly and annual rates and the Total Effective Cost, the CET. This allows you to make the decision based on your own invoice numbers, rather than relying on an average market rate.
Start with the invoice, not the offer that seems lightest
Copy five details before opening any simulator: total invoice value, minimum payment, charges informed for the next period if you pay the minimum, installment options with term and value of each installment and the CET of each alternative. If there is an effective monthly and annual fee, record that too. These numbers are a snapshot of what the issuer is offering in that cycle.
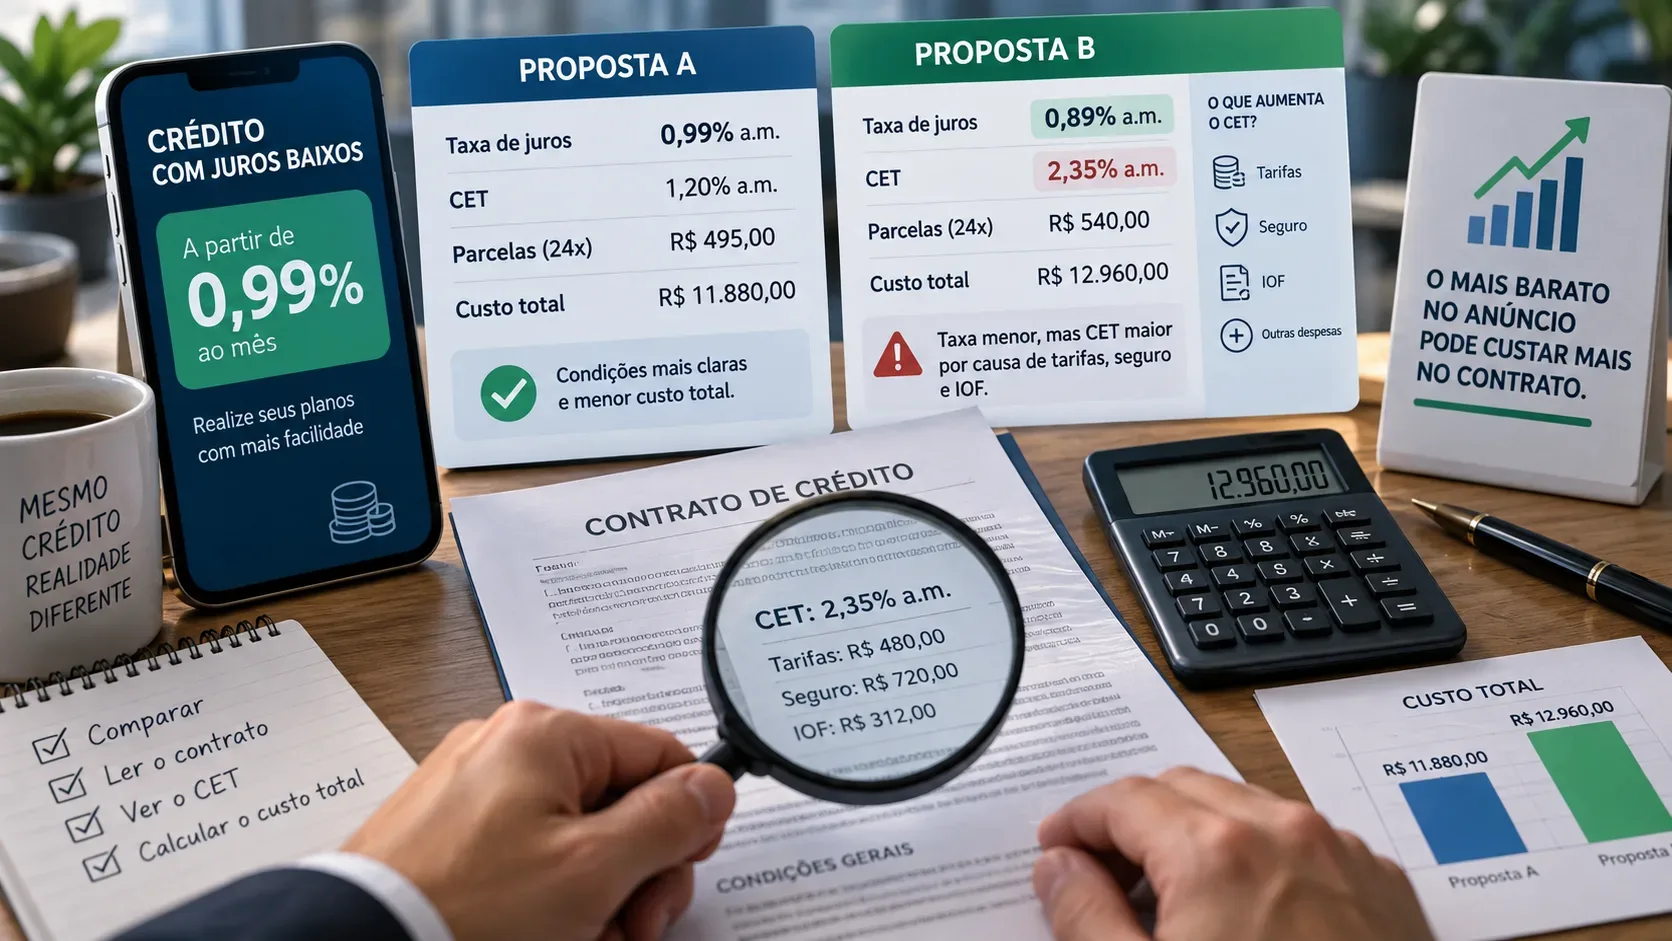
The CET is more useful than just looking at the interest rate because it brings together the charges and expenses of the operation. In credit, this may include interest, taxes, fees, insurance and other related expenses. Therefore, two proposals with the same announced rate
may have different CET. To compare external loan offers with invoice installments, use the CET of the final proposal, not a promotional rate highlighted on the home screen.
Still, CET does not replace the total amount payable. A longer operation may have a lower annual CET and, even so, end up with a higher total disbursement because you spend longer paying interest and charges. The comparison needs to use both measurements together.
Minimum payment is a very short-term credit
Paying the minimum does not mean getting a discount or turning the bill into a cheap installment. The amount that remains unpaid goes into revolving credit and returns on the next invoice with interest and charges. The revolving bill can be used until the next invoice is due, generally a cycle of up to 30 days. If the balance remains unpaid after this period, it cannot remain in the same revolving account indefinitely; the solution is to pay off or migrate to a form of installments under the applicable conditions.
That changes the question. The minimum can be compared with other alternatives only if you know what you will do on the next maturity date. If there is a practically certain and sufficient inflow of money to bring the balance to zero in the following month, the minimum can act as a bridge to a cycle. If you already know that you won't have the money to pay the next bill, using the minimum only postpones taking out a longer credit and adds the cost of the revolving bill along the way.
The invoice itself should show how much you will be charged in the following period if you only pay the minimum. This field is more important for the decision than the percentage of the minimum. There is currently no fixed national percentage of 15%: the minimum value is defined by the institution in accordance with the product and customer rules.
Invoice installments and loan need to finance the same amount
To find out if a personal loan is really better than paying the bill in installments, standardize the problem. If the invoice is R$4,000 and you can put R$1,000 out of your own pocket, compare alternatives that finance the same R$3,000. If a loan simulator shows R$3,000 in contracted value, confirm that this is also the net amount that will be added to the account after taxes, insurance or other charges. The liquid money must be sufficient to pay the portion of the bill that you decided to pay with the loan.
Then match the deadline whenever possible. Comparing a six-month installment with a twenty-four-month loan may artificially favor the lower installment. First make a comparison in close terms. Only then test for a longer period of time to find out how much it costs to buy a break in the budget.
On the same sheet, record how much comes out of your pocket today, how much will be financed, number of installments, value of each installment, CET and sum of all payments. O
lower CET helps identify structurally cheaper credit; the lowest total payable shows the cost in reais; and the installment tells you whether the solution survives your actual budget.
Numerical example: the smallest payment of the month does not decide alone
Consider a fictitious invoice of R$4,000. The minimum payment is R$400, and the invoice states R$360 in charges for the following period if only the minimum is paid. If the person pays R$400 now and manages to pay off the entire remaining balance on the next due date, the amount linked to this invoice would be approximately R$4,360: the R$400 paid now, the R$3,600 that remained outstanding and the R$360 in reported charges, not counting new purchases or other entries.
This R$4,360 is only a final cost if there is money to close the debt the following month. If there isn't, the account hasn't finished yet. The balance will need another form of financing, and the cost of this new stage is also included in the decision. This is why the minimum payment may seem cheap looking at just this month and expensive when the real horizon is several months.
Now suppose that the person can pay R$1,000 today and needs to finance R$3,000 for six months. In a fictitious simulation, the invoice installment plan offers six installments of R$620, totaling R$3,720 in financing and R$4,720 in disbursement when added to the R$1,000 paid in cash. The reported CET is around 113% per year.
An external loan, also fictitious, releases R$3,000 net and charges six installments of R$585. The financing amounts to R$3,510 and, with the R$1,000 used in the invoice, the total disbursement reaches R$4,510. The reported CET is around 73% per year. In this design, the loan costs R$210 less and also reduces the monthly installment by R$35.
But imagine a third loan offer with eighteen installments of R$240. The installment seems much more comfortable, but the installments total R$4,320; With the R$1,000 placed at the beginning, the total disbursement increases to R$5,320. Even though the annual CET is attractive, the longer term can make the total in reais surpass shorter alternatives. The example numbers are illustrative only; the method is what must be repeated with the real proposals.
First eliminate what doesn't fit; then choose the lowest cost
The cheapest proposal in total is no use if the installment leaves you lacking money for housing, food, transport, health and other essential expenses. Before comparing credit, define a ceiling on the installment that the budget can support without depending on using the card again to close the month. If the chosen solution requires going back to the card to pay basic expenses, the debt tends to recover.
At the same time, don't make the smallest portion the main objective. Extending the term reduces the monthly disbursement, but can increase the total paid. The balance is finding the lowest cost among the options that really fit. When none
installment fits, the problem is no longer just choosing between minimum, installment and loan; This is a sign that the renegotiation needs to consider the budget and debts as a whole.
The card's interest ceiling is a protection, not a cost target
Since January 2024, interest and financial costs accumulated on the part of the invoice that remained unpaid or was paid in installments with interest are subject to a limit equivalent to 100% of the original value of that debt. In simple terms, the rule prevents interest and financial charges on revolving and installment payments from continuing to grow without this ceiling.
That doesn't make the rotary cheap. A cost that comes close to the debt principal remains high for the household budget. The cap should be understood as a barrier against extreme growth in charges, not as a justification for accepting the first available proposal.
When portability becomes a fourth alternative
Before due date, taking out a loan from another bank to pay off the invoice is a new credit operation. Portability is another thing. It becomes relevant when there is already a debt balance on the card in credit operations, such as revolving or invoice installments, and another institution offers better conditions to assume this balance.
The portability of the card's outstanding balance is regulated and can be requested by the debtor from the institution to which he intends to take the debt. The proposal must contain information such as interest rate, CET, term, amortization system and value of installments. The transfer cannot have communication costs between institutions passed on to the client, and the originating institution must accept portability when the operation requirements are met. The process can take up to seven business days, so it should not be treated as an instant solution to an invoice due on the same day.
If the bank of origin makes a counter-offer to avoid leaving, the comparison remains the same: term, CET, installment and total cost. The counter-proposal must be consolidated within a period equivalent to that of the competing proposal to allow comparison. It is also worth being wary of offers that mix portability with extra money, called change. Additional credit should only enter the account if there is a real need, because it increases the financed balance.
A decision script that can be repeated on every invoice
If you can pay off the remainder in full on the next due date, use the next period's charges field to measure how much it costs to go through a single cycle on the revolving schedule. Compare this cost with any very short-term alternative that is available and only choose the minimum if the next payment is compatible with a concrete cash inflow, not with the hope that the month will be better.
If you need several months, compare invoice installments and loans with the same net amount financed and close deadlines. Give preference to the proposal that has the lowest total cost among those that fit into the budget, using the CET to confirm that tariffs, taxes and other charges are not hiding a more expensive operation.
If the debt has already become a balance financed on the card, also ask for a portability proposal. At this stage, it can function as a fourth alternative and increase competition between institutions. The central point remains the same: no modality is automatically best. The answer lies in the concrete numbers on your invoice and the proposals you received.
The decision improves a lot when you stop asking just “which portion is smaller?” and starts to ask “how much do I actually receive or finance, how much do I pay in total, for how long and will this payment last without creating another debt?”. This is the basis for comparing credit without trading immediate relief for a higher, less visible cost.