Credit portability existed in Brazil before Open Finance. What changes is the addition of a standardized digital route through which the institution that wants to receive the debt can, with the customer's authorization, obtain the necessary contract data and exchange information with the original creditor. The traditional portability route has not been eliminated.
What Open Finance changes in credit portability
In the Open Finance flow, the customer starts the journey with the proposed receiving institution — the bank or lender to which the customer intends to move the debt. That institution can use shared data to identify eligible contracts, prepare an offer and send the portability request to the original creditor. The Central Bank of Brazil describes this alternative as a digital, standardized process that can be followed through the institutions' electronic channels. See the Central Bank's explanation of credit portability through Open Finance.
This does not mean that a debt is transferred automatically just because the customer authorized data sharing. A new offer still has to exist, the customer must accept its terms, and the institutions must complete the communication, settlement and confirmation steps required by the rules.
What the three-business-day deadline actually means
The key point is this: three business days do not necessarily represent the total time for the entire portability process. The rule shortens a specific stage to up to three business days when the exchange of information between institutions takes place through Open Finance.
According to the Central Bank's step-by-step guidance, after the proposed receiving institution sends the request, the original creditor must request the transfer of funds needed to complete the portability. Under the traditional route, this stage can take up to five business days; when information is exchanged through Open Finance, the deadline is up to three business days. After the funds are transferred, the original creditor still has up to two business days to confirm receipt or report an impediment and, if the operation is completed, send the document proving completion. Check the official step-by-step guidance.
| Stage | What happens | Deadline highlighted by the Central Bank |
|---|---|---|
| Portability request | The proposed receiving institution sends the request to the original creditor. | The three-day period does not start before a valid request exists. |
| Information exchange through Open Finance | The original creditor processes the request and asks for the transfer of funds. | Up to 3 business days. |
| After the transfer | The original creditor confirms receipt or reports an impediment and, when completed, sends proof. | Up to 2 business days from the transfer. |
From the customer's perspective, the overall time may also include earlier steps such as consent, contract selection, offer analysis and a possible counteroffer. For that reason, saying “portability in three days” can create the wrong expectation about the total duration.
How the customer journey works
- Choose the proposed receiving institution. This is where the customer looks for the option to move the credit operation.
- Authorize the required sharing. The journey depends on valid consent so the proposed institution can access the customer's relevant data and credit-operation information. If there is no valid consent, the customer must be directed to the data-sharing consent journey.
- Select an eligible contract. The proposed institution should show contracts that can enter the portability flow, linked to creditors for which the applicable data sharing and infrastructure are available.
- Review the offer. The new institution presents the terms of the credit operation that would replace the original one.
- Accept or reject. The original creditor may present a counteroffer through its channels, but the decision remains with the customer.
- Track completion. After acceptance, the request, fund transfer and completion-confirmation stages follow.
The Open Finance Customer Experience Manual details this journey and requires the proposed institution to display enough information for the customer to compare the original contract with the new offer. See BCB Normative Instruction 760/2026.
Which contracts are within scope
The first product selected by the Central Bank for implementation was unsecured, non-payroll-deducted personal credit, also referred to as Crédito Pessoal Clean. The Central Bank's rollout schedule placed this product first and left other credit categories for gradual expansion.
An important wording change arrives in November. Version 8.0 of the Open Finance Data and Services Scope Manual, issued through BCB Normative Instruction 759/2026, takes effect on November 3, 2026 and adds a specific section on credit portability. It describes the eligible category as personal credit without payroll deduction. The manual states that, with the customer's prior consent, original creditors must make information about contracts in this category available so proposed institutions can prepare offers. Read version 8.0 of the Scope Manual.
This should not be interpreted as automatic eligibility for every consumer debt. The contract must fall within the eligible category, the relevant institution must participate in the applicable arrangement, and the journey depends on the infrastructure and APIs made available by participants.
What enters the November phase — and what does not enter automatically
Two different developments coincide in November 2026 and should not be confused:
- On November 3, Scope Manual v8.0 takes effect. It formally adds the credit-portability service and the scope for non-payroll-deducted personal credit to the technical manual.
- The Central Bank's roadmap points to the next product category in November: payroll-deducted personal credit, initially for federal civil servants.
This roadmap does not mean that every payroll loan becomes available all at once on November 3. The official communication describes a gradual rollout starting with payroll-deducted credit for federal civil servants. The roadmap does not support the conclusion that INSS payroll loans, private-sector payroll loans or all other credit categories automatically enter on the same date. The Central Bank says other categories will be studied and added later. See the Central Bank's published roadmap.
It is also useful to distinguish a planned product date from availability in every app. Actual availability depends on implementation by participating institutions and the technical rules in force when the customer makes the request.
What the customer consents to and which data enter the flow
Credit portability through Open Finance does not imply unrestricted access to the customer's entire financial life. The journey depends on consent to share the necessary data and on identifying the specific contract to be moved. Scope Manual v8.0 lists minimum data such as customer information, the proposed institution, the original creditor, the credit operation to be moved and the offer presented.
In the customer experience described by the Central Bank, the proposed institution must allow the customer to choose the contract and review the offer's terms. If a portability request is already in progress for a contract, that contract should appear as unavailable for a new selection, with an indication that a request is already underway.
How to compare an offer without looking only at the installment
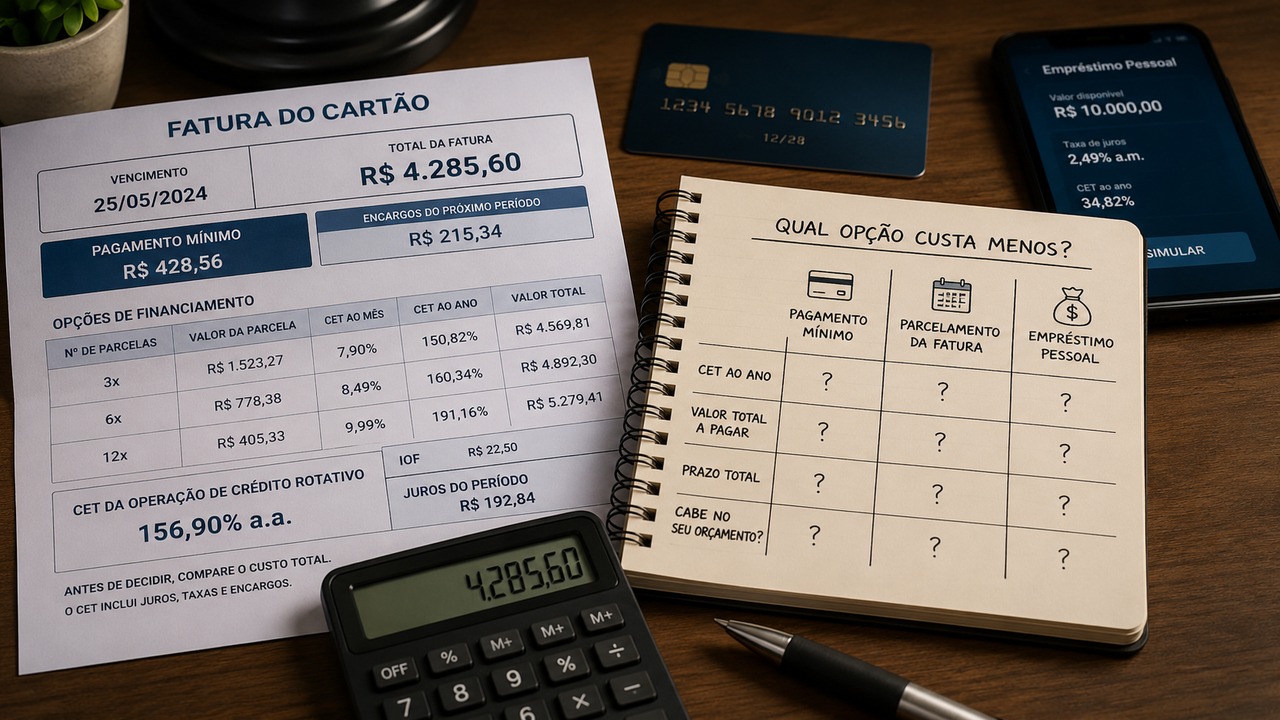
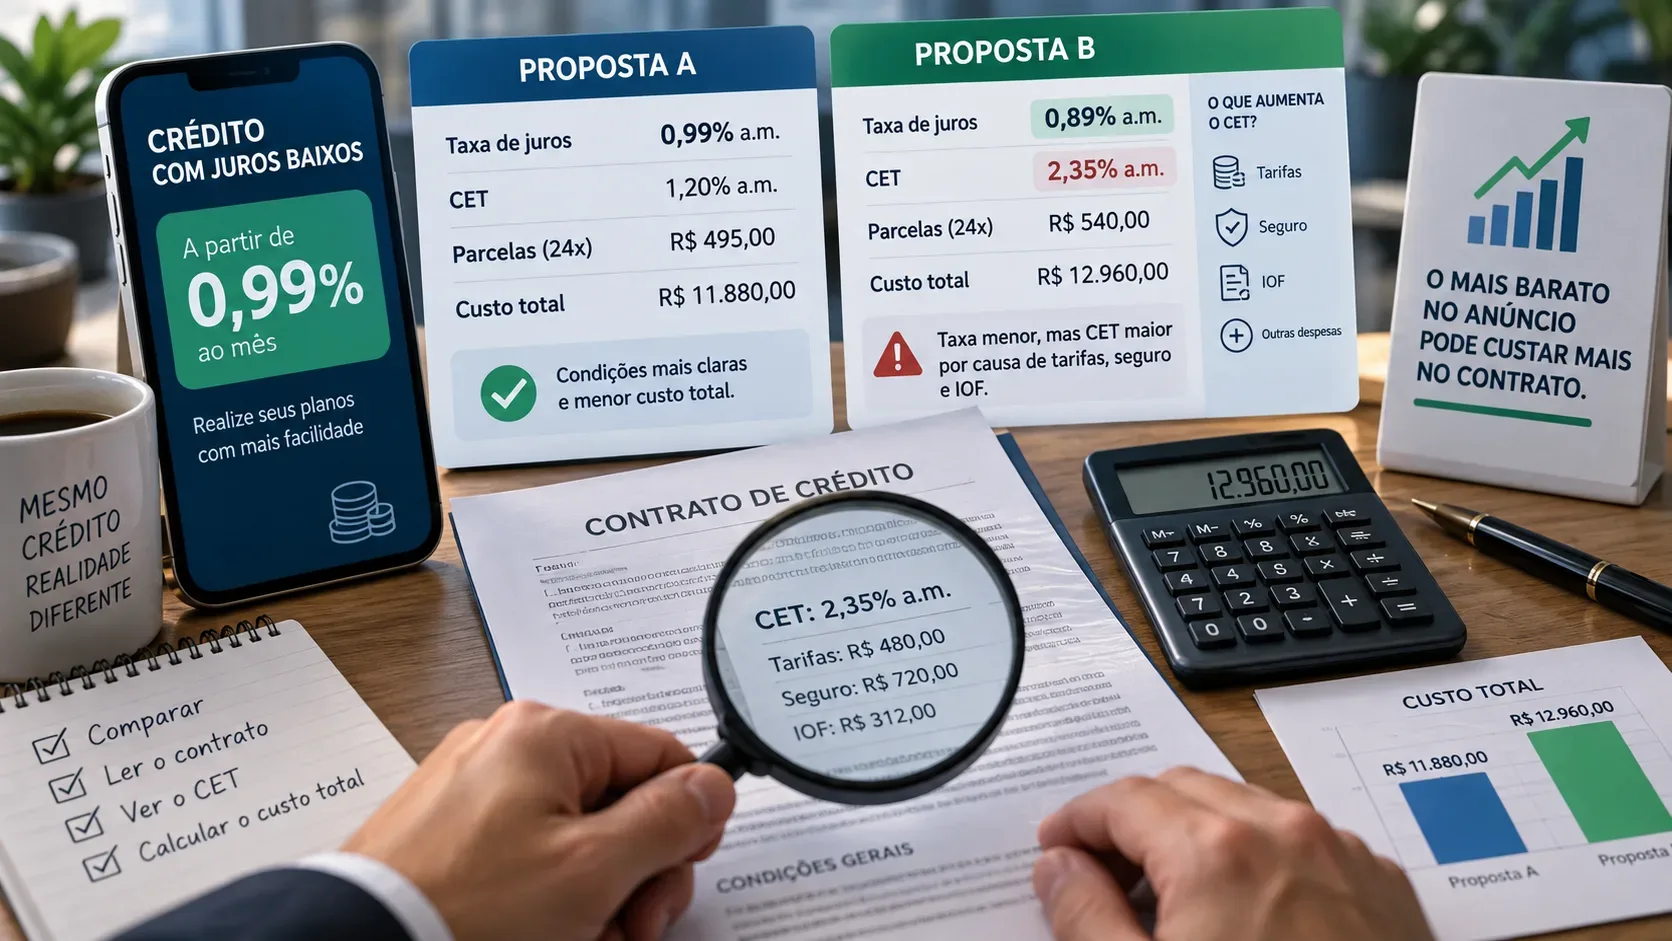
A lower monthly payment by itself is not proof that the new operation is cheaper. The key metric for comparing the cost of credit is the Custo Efetivo Total (CET), or Total Effective Cost, because it consolidates interest, fees, taxes and other expected charges. The Central Bank requires the portability offer to include the CET and other relevant conditions. See the information required in a portability request.
Before confirming, compare side by side:
- the current contract's CET and the new offer's CET;
- effective interest rate;
- installment amount;
- number of installments and remaining term;
- total amount to be paid;
- amortization system;
- any index or remuneration basis, when applicable.
The Customer Experience Manual requires the proposed institution to highlight the differences in monthly amount and total amount between the new offer and the original contract. If the new installment is higher, acceptance must be preceded by a specific confirmation from the customer.
Practical checklist before confirming portability
- Confirm that the displayed contract is exactly the one you intend to move.
- Check that the institution receiving the debt is the proposed institution you selected.
- Read the CET, term, installment and total amount, not only the advertised interest rate.
- Check whether the current institution has made a counteroffer and compare both on the same basis.
- Do not treat three business days as a guarantee that the entire process will be completed within three days.
- Track the status through the institution's official channel and keep proof of the request and completion.
In practical terms, Open Finance reduces friction and standardizes information exchange, but it does not remove the need to review the offer or make every debt automatically portable. For November 2026, the most important distinction is between the effective date of Scope Manual v8.0 and the gradual expansion planned for payroll-deducted credit for federal civil servants.