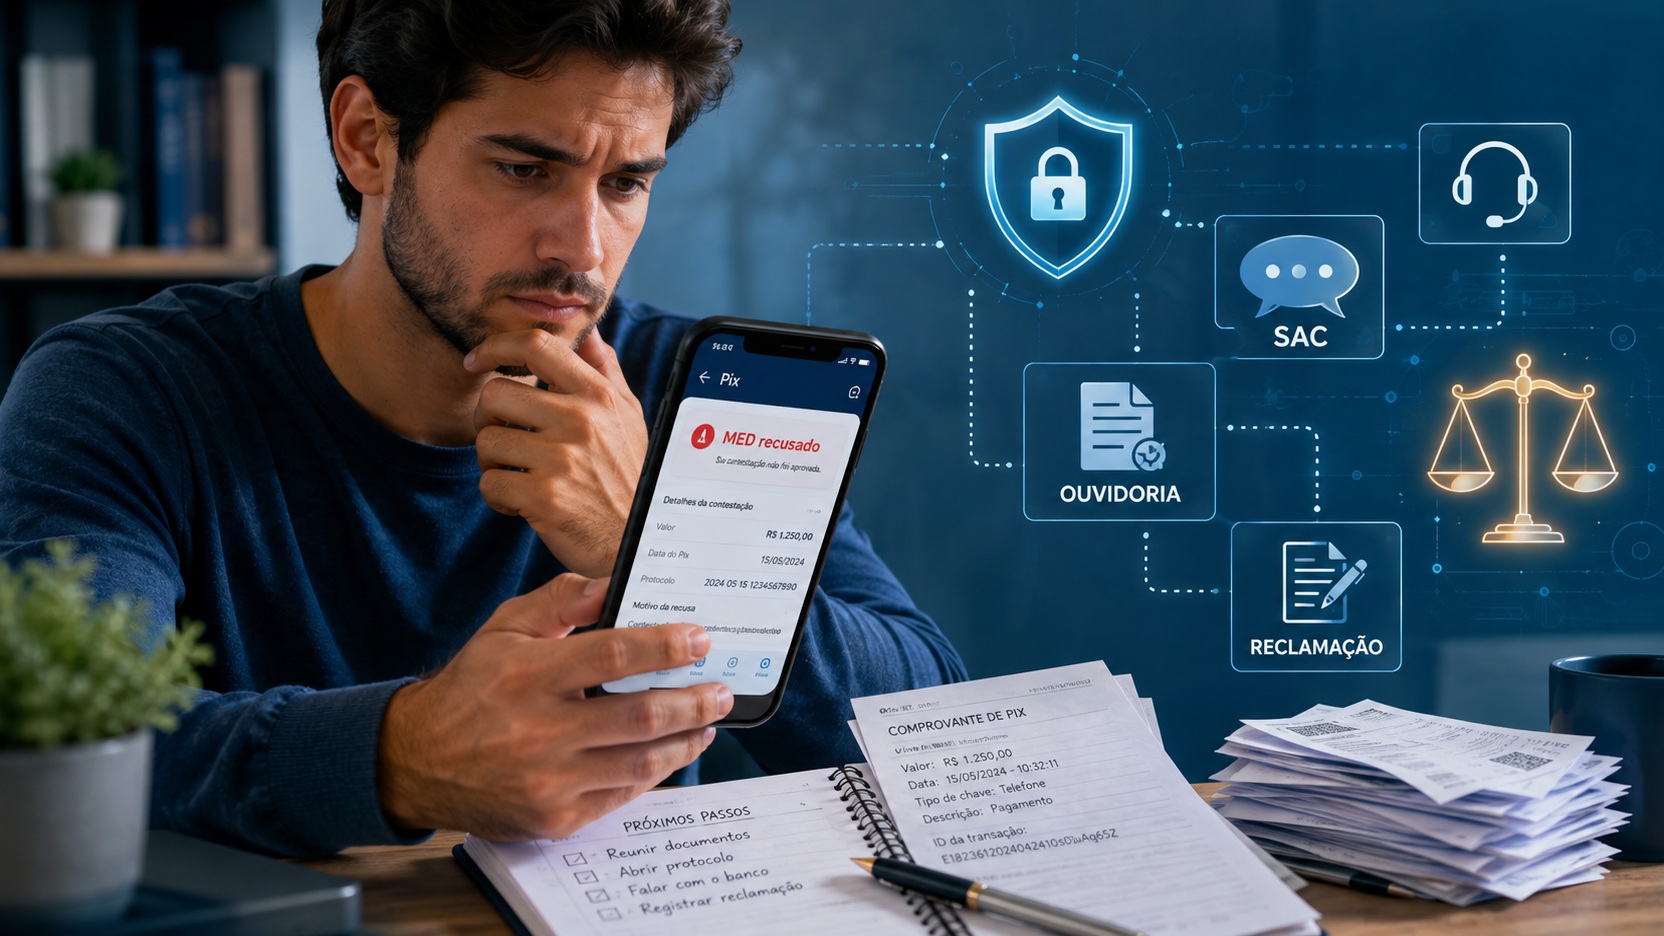
Receiving a “MED declined” response after falling for a scam can give the impression that the case is over. It's not necessarily like that. The Special Return Mechanism is Pix's own procedure to try to recover resources in situations of fraud, scam or crime, but the decision within the MED does not replace the bank's service channels, consumer protection mechanisms or any legal analysis of the case.
The first step after denial is not to file complaints everywhere at the same time. It's understanding exactly what was denied. A refusal because the bank concluded that the situation does not fall under the MED is different from a case where fraud was recognized but no money was recovered, or only part of the money was returned. This distinction defines the next path.
Since February 2, 2026, the expanded tracking functionality announced by the Central Bank for the MED has become mandatory, allowing recovery to also search for resources in subsequent accounts identified in the money flow. Still, the mechanism does not guarantee a full refund. The existence of tracking does not create a balance where there are no resources nor does it turn the MED into a card-like chargeback.
Before appealing: find out the reason for the denial
The short message displayed in the app does not always explain what happened. Therefore, ask the bank for a clear response, preferably in writing, with the dispute protocol, the opening date, the final status and the reason for the conclusion. The objective is to separate a merit denial from an unsuccessful recovery.
When the bank says that the case does not fit into the MED
MED is not useful for any Pix that the payer wants to undo. Central Bank rules direct it to fraud, scams, crimes and specific hypotheses of operational failure. O
mechanism is not intended to resolve simple commercial disagreements, purchase regrets or Pix sent by mistake to the wrong person. There is also a deadline: the complaint to activate the MED must refer to a transaction carried out no more than 80 days ago.
If the bank's justification was “it does not fit into the MED”, check if it corresponds to what actually happened. In a scam, for example, the fact that the victim himself confirmed the Pix does not mean, in itself, that the situation is a mere typing error or a commercial disagreement. The bank must analyze the report and framing of the case in accordance with the applicable rules.
When there was a fraud analysis, but there was no full recovery
Another situation is for the bank to inform you that the MED was processed, but the amount returned was zero or less than the loss. In this scenario, the main point is not just to ask “why was the MED denied?”, but to confirm whether fraud was recognized, what steps were taken and what was the result of the recovery of values.
MED 2.0 expanded tracking beyond the first account that received Pix. Even with this progress, the refund may be partial or non-existent when the resources are not located or are not available in the accounts reached by the procedure. An insufficient recovery, therefore, should not be automatically confused with a conclusion that “there was no coup”.
When the answer is generic or contradictory
Messages such as “request not approved”, “dispute unfounded” or “no possibility of refund”, without explaining the reason, are of little use in deciding what to do next. In this situation, the immediate objective is to obtain a verifiable justification. Ask if the bank considered the case to be outside the scope of the MED, if the fraud was not confirmed, if there were no recoverable resources or if another operational impediment occurred.
This response must be compared with the documents already sent and with the original report. If there is a factual error — incorrect date, wrong transaction, incomplete description of the scam or evidence that was not considered — record this objectively at the next appointment.
Gather documentation before changing channels
A good subsequent challenge depends less on repeating that “it was a coup” and more on organizing what can be demonstrated. Keep the Pix receipt, the transaction identifier, date, time, value, name or displayed data of the recipient, conversations with the scammer, advertisements or pages used in the fraud, emails, screenshots, bank protocol number and the response that denied or terminated the MED.
If there is still no police report, the Central Bank advises victims of scams to register it, presenting documents that prove what happened. The report does not replace bank analysis or guarantee a refund, but it helps to formalize the narrative and can be useful in later stages.
Also preserve any evidence that the transaction deviated from your usual pattern, if that is part of the case. There is no need to transform the complaint into a legal thesis; simply record verifiable facts, in chronological order, and indicate which solution
is being requested.
Return to the bank first when there is no explanation or review
The bank's initial channel or SAC is suitable for requesting details of the decision, correcting incorrect information and registering a new statement about the way the dispute was handled. Use the previous protocol as a reference and do not present the case as if it were a completely new occurrence.
The request can be simple: inform the specific reason for the denial, clarify whether the case was considered outside the scope of the MED or whether there was recovery without sufficient balance, indicate the final result of the procedure and record the new documents presented. The more objective the request, the easier it will be to identify whether the institution responded to the central point.
If the first response does not resolve the problem, the next step within the institution itself is usually the ombudsman.
When the bank ombudsman makes sense
The ombudsman is a channel within the institution designed to deal with complaints that have not been adequately resolved through previous channels. For a denied MED, it is especially useful when a protocol already exists and the problem is a lack of explanation, a possible inconsistency in the analysis or the need to review the institutional response.
When contacting the ombudsman, provide the SAC or original service protocol, reproduce the reason for the denial and highlight exactly what remains unanswered. Avoid sending just a long narrative of the scam without indicating which decision needs to be reevaluated.
The ombudsman can review the treatment given to the case and respond on behalf of the institution, but it must not be presented as a guarantee of a refund. If the impasse continues, there are external channels with different functions.
Complaint to the Central Bank: useful for supervision, but not a reversal order
A complaint to the Central Bank is often interpreted as a resource capable of forcing the bank to return the money. This expectation is incorrect. The official service itself informs that the Central Bank does not interfere in the individual case or in the contractual relationship between the client and the financial institution.
When a complaint is registered with the BC against a supervised institution, the response is given by the complaining bank or institution itself, which has up to 10 working days to respond in writing. The complaint also feeds the supervision and inspection of the financial system. The Central Bank makes it clear that registration does not guarantee a solution to the problem.
Therefore, this channel makes more sense when the consumer wants to formalize a possible failure in procedure, service or compliance with the rules applicable to Pix and MED. It should not be treated as a “second MED” nor as an instance that simply replaces the bank's analysis and determines the credit value.
Consumidor.gov.br: direct negotiation registered with the company
Consumidor.gov.br is a free public service that allows direct communication between
participating consumers and companies. To register and track the complaint, you must use a silver or gold level gov.br account. The company has up to 10 days to respond.
In the case of a denied MED, the platform can be useful when the objective is to formally register the consumer conflict and obtain a structured response from the bank. Attach proof of Pix, the service protocol, the MED denial and the documents that support the report. Explain what has already been tried and what solution is being requested.
It is important to know the channel limit. Consumidor.gov.br itself informs that the platform does not constitute an administrative procedure and cannot be confused with Procon, inspection bodies or the Judiciary. If the company's response does not resolve the problem, the consumer may seek other avenues.
Procon: consumer protection and administrative handling of conflicts
Procon is a consumer protection channel and can be sought when the conflict with the financial institution remains unresolved. The form of assistance and the procedure vary depending on the state or municipality, but the Central Bank expressly includes Procon among the options available for problems with financial institutions.
For a case of Pix and MED, the usefulness of Procon is in taking the conflict to the consumer protection structure, with organized documentation and history of previous services. Procon is not a technical Pix tool and does not directly execute a refund in the banking system. Its role is different from the MED and also different from the supervision carried out by the Central Bank.
If the company does not participate in Consumidor.gov.br, or if the platform has already been used without satisfactory results, Procon can become a particularly relevant path for guidance and attempts at an administrative solution.
How to choose the next channel according to the response received
If the denial does not explain the reason
Start with the bank and, if necessary, with the ombudsman. The objective is to obtain a specific answer about the framework and result of the MED. Without this, any external complaint becomes more difficult to formulate and may end up repeating information that the institution already has.
If the bank says the case was not eligible for MED, but the report is a scam
Ask for the reasons for this conclusion and check whether the situation was classified correctly. If the ombudsman maintains a response that you consider incompatible with the facts or the rules of the mechanism, a complaint to the Central Bank may record the possible procedural failure. In parallel, Consumidor.gov.br or Procon can be used to address consumer conflicts.
If the fraud was recognized, but the money did not return or only partially returned
Ask the bank to make it clear whether the result was an absence or insufficient resources recovered. This avoids insisting on a “reversal of the negative” when the real problem was financial recovery. Then, evaluate the consumption channels to discuss the response.
institution and, if there are elements that indicate a possible failure of the banking service, seek individualized legal advice.
If the bank has already responded, the ombudsman maintained the decision and the consumer channels did not resolve it
At this point, the question is no longer just “how to reopen the MED”. It may be necessary to assess whether there is a legal claim against the institution, the fraudster or others involved. Consumidor.gov.br recommends, when the solution through the platform is not satisfactory, contacting Procons, Public Defenders, Special Civil Courts or other competent bodies.
MED denied does not decide alone whether the bank is responsible for the loss
The result of the MED and the possible civil liability of the financial institution are related matters, but not identical. MED is Pix's operational mechanism for trying to retrieve values. A discussion about the bank's responsibility requires analyzing the circumstances of the scam, the security measures adopted, the behavior of transactions, the available evidence and other elements of the specific case.
Jurisprudence also does not transform every scam into automatic liability for the bank. Recent decisions by the Superior Court of Justice reinforce that the conclusion depends on demonstrating a failure to provide the service and the particularities of each situation. Therefore, an administrative denial should not be treated either as definitive proof that the bank is correct, nor as proof that it obligatorily must compensate.
When the damage is relevant, there are signs of a security breach or the controversy depends on legal interpretation, it is worth seeking an individual analysis with a qualified professional or legal assistance service. This step is different from filing a complaint with BC, Consumidor.gov.br or Procon.
What not to expect from external channels
None of these channels should be presented as a chargeback button. Complaints to the Central Bank do not generate an automatic refund and are not decided by the BC in favor of the consumer. Consumidor.gov.br creates a registered negotiation with the company, but it is neither an administrative nor a judicial process. Procon acts in consumer protection, but does not replace Pix's technical mechanism. And any legal action depends on facts, evidence and specific grounds.
The usefulness of these paths lies in different functions: obtaining a more complete institutional response, reviewing the service, recording possible regulatory non-compliance, seeking a consumer solution or taking the controversy for legal analysis when necessary.
A practical sequence after refusal
After a denied MED, the most consistent sequence is to identify the exact reason for the decision, save the response and protocols, gather evidence of the scam, request clarification or review through the bank's channel and contact the ombudsman if previous assistance does not resolve the issue. If the problem persists, choose the external channel according to the objective: Central Bank to register a complaint about a supervised institution and
contribute to supervision; Consumidor.gov.br for registered direct negotiation; Procon for consumer protection; and legal guidance when the controversy requires assessing rights, responsibility and possible legal action.
The main point is not to confuse “MED denied” with “there is nothing more to do”. The denial ends a specific stage of the return mechanism, but the next path depends on the reason for the denial. The clearer it is about what the bank decided and what evidence supports the case, the greater the chance of using the next channel for the correct purpose — without creating the false expectation that a complaint alone will guarantee a chargeback.