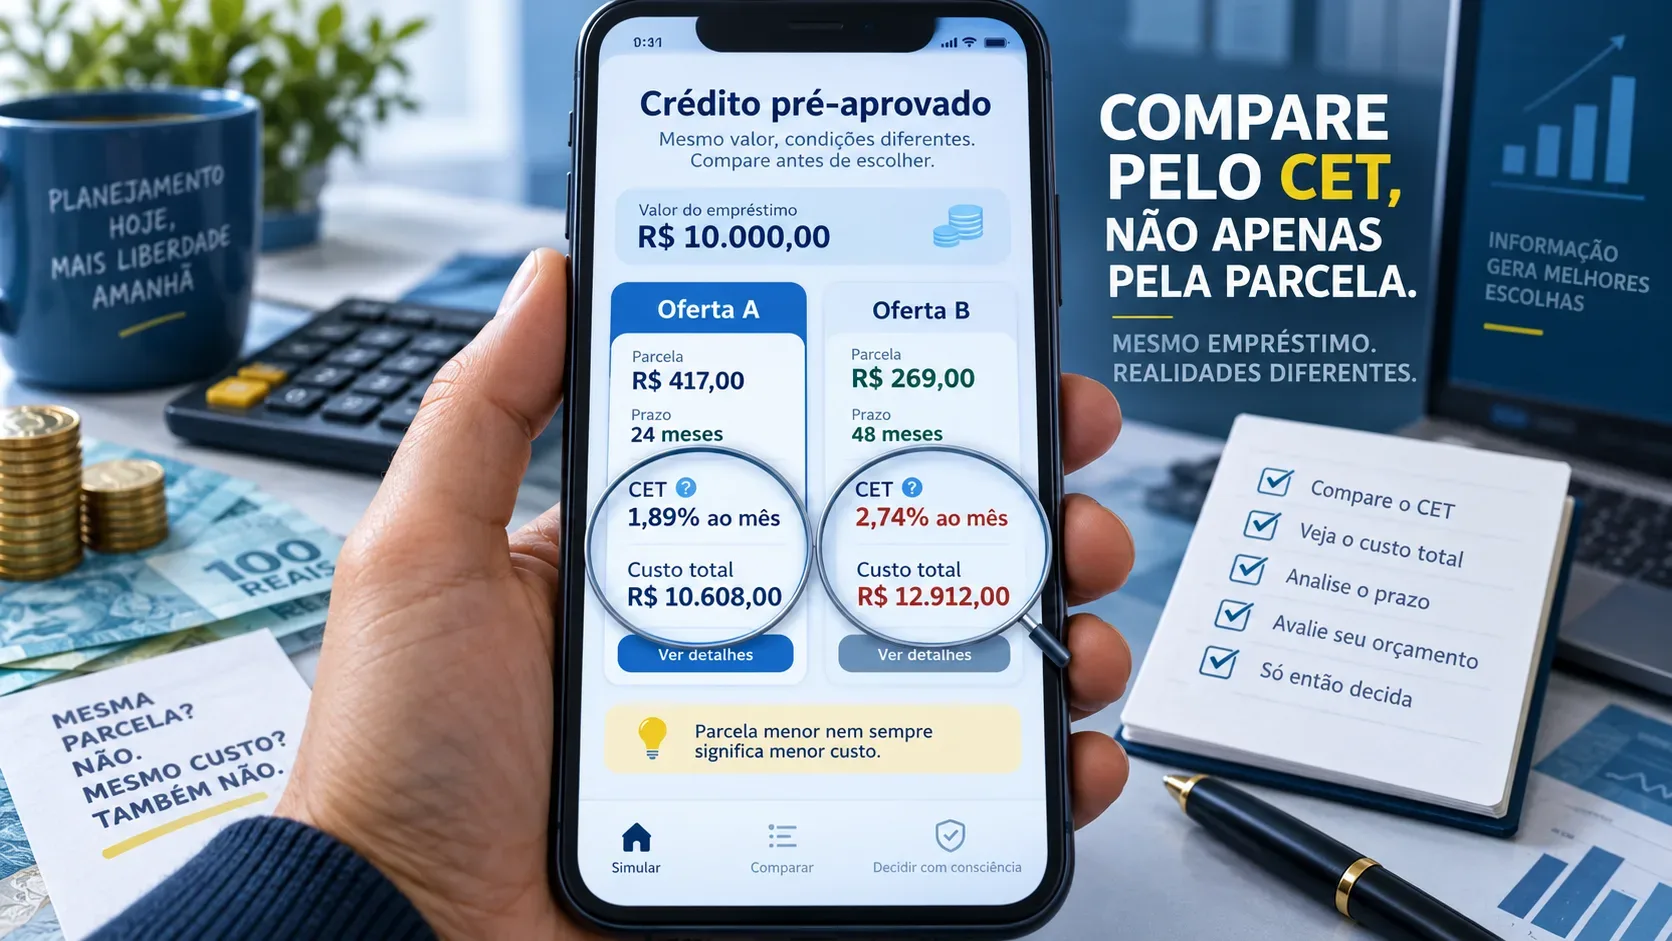
Pre-approved credit in an app should not be compared by the installment alone. A lower monthly payment may ease short-term cash flow and still lead to a higher total outlay when it comes with a longer term, a higher rate or additional charges. To compare offers, look at the Total Effective Cost (CET, the Brazilian regulatory measure), the term, the net amount you actually receive and the sum of all installments.
What CET shows and why it is more useful than the interest rate alone
CET is a rate that consolidates the charges and expenses associated with a credit operation. Under CMN Resolution No. 4,881/2020, the calculation considers the credit granted and the amounts charged to the borrower, including principal repayments, interest, fees, taxes, insurance and other expenses linked to the transaction. Brazil’s Central Bank also describes CET as information designed to make the cost of different credit offers comparable.
This helps avoid a common mistake: choosing an offer only because its advertised interest rate looks lower. Two offers may have similar interest rates and different overall costs because of fees, insurance or other charges. The reverse can also happen: a slightly higher nominal interest rate may produce a lower CET if the other charges are smaller.
Brazilian rules require CET to be disclosed before the contract is signed and require the institution to present a calculation statement. That statement must show the components of the transaction’s cash flows and the sum of the installments. In an app, therefore, look for areas such as “details”, “terms”, “credit information”, “CET” or “contract” before tapping “accept”.
Why the lower installment can cost more
Consider a hypothetical example in which both offers deliver the same net BRL 10,000 to the customer and there is no upfront charge outside the installments. The figures are only meant to illustrate the comparison logic; the actual CET must be calculated and disclosed by the institution for each offer.
| Item | Offer A | Offer B |
|---|---|---|
| Net amount received | BRL 10,000 | BRL 10,000 |
| Installment | BRL 520 | BRL 320 |
| Term | 24 months | 48 months |
| Sum of installments | BRL 12,480 | BRL 15,360 |
| Approximate annual CET in the example | 24.66% p.a. | 25.47% p.a. |
Offer B has an installment that is BRL 200 lower, but it lasts another 24 months. By the end, payments add up to BRL 15,360 versus BRL 12,480 for Offer A: a BRL 2,880 difference. The installment describes the monthly impact only; by itself, it does not describe the price of the credit.
This is why it helps to separate three questions: how much does the money cost over time? — answered by CET; how much money leaves your pocket in total? — answered by the sum of installments and other payments; and does the installment fit the budget? — answered by your personal cash flow.
Checklist: what to find in the app before accepting
- Net amount disbursed: confirm how much will actually reach your account. If a fee or insurance premium is deducted before disbursement, two offers advertised as “BRL 10,000 in credit” may deliver different net amounts.
- Annual CET: use the annual rate disclosed to compare the consolidated cost. CMN Resolution No. 4,881 requires CET to be expressed as an annual percentage rate.
- Interest rate: check the effective monthly and annual rates, but do not treat them as substitutes for CET.
- Number and value of installments: a lower installment often comes from a longer term.
- Sum of installments or total amount due: this is the figure in currency that helps make the accumulated outlay visible.
- Fees, taxes, insurance and other costs: check for optional services or embedded charges and how they affect the transaction.
- Dates and grace period: check when the first installment is due. Delaying the start of payments can change the cost of the offer.
How to compare offers with different terms
When the terms differ, no single column can settle the whole decision. Use a sequence:
- Make the object of comparison equivalent: compare offers for the same need, preferably with the same net amount received and the same type of credit.
- Compare CET: it normalizes transaction costs into an annual rate and helps identify which offer charges more for the money over time, considering the expenses included in the calculation.
- Compare the total in currency: longer terms can substantially increase the sum paid even when the installment is lower. An offer with a slightly lower CET may also produce a higher total outlay if the term is much longer.
- Test the installment against your budget: the mathematically cheaper option is not useful if its payment makes the budget unworkable and increases the risk of late payment.
A practical way to think about it is: CET measures relative cost; total paid measures accumulated outlay; the installment measures monthly pressure. Read all three together.
Interest, CET and total cost are not the same thing
The interest rate is the price charged for the credit itself. CET incorporates the interest rate and the other charges covered by the regulation. The total cost in currency shows how much will be paid over the life of the contract under the offer’s terms. That is why looking only at a monthly rate or only at the installment can hide part of the comparison.
Some credit operations also use benchmarks that change over time. CMN Resolution No. 4,881 states that floating parameters or price indexes whose value changes during the contract are not included in the CET calculation, but must be disclosed in the statement. When an offer has this type of component, the terms require additional attention because future cost may depend on the benchmark’s movement.
What to do if CET is hard to find
The fact that an offer is labeled “pre-approved” does not remove the disclosure requirement. According to Brazil’s Central Bank, CET must be provided before contracting and the calculation statement must be presented to the prospective borrower. If the first screen highlights only “available money” and “installment”, continue to the terms screen, but do not complete the transaction until you have found CET, the term and the total amount payable.
It is also worth checking the contract or transaction document. The Central Bank states that loan and financing contracts must include, among other items, effective monthly and annual interest rates, taxes, fees, other expenses and CET.
A simple decision rule
Before accepting pre-approved credit in an app, compare in the right order: same net amount → CET → term → total amount payable → installment that fits the budget. If an offer wins only because its installment is smaller, but requires many more months and raises the total outlay, it is not automatically the cheaper option.
CET is the best starting point for comparing the financial price of offers; the sum of installments shows the consequence in currency; and your personal budget determines whether the obligation is sustainable. Reading these together turns an “available credit” screen into a comparable, informed credit decision.